
Life insurance is more than just a safety net for your family. It can also affect your taxes, but many people are unsure when life insurance is tax deductible. Understanding the rules can help you save money, avoid surprises, and make better financial decisions.
Here’s a practical guide to what life insurance is tax deductible, who can benefit, and common mistakes to avoid.

The Basics: Is Life Insurance Tax Deductible?
For most people, life insurance premiums are not tax deductible. When you buy a policy for yourself or your family, the IRS treats premiums as a personal expense—just like groceries or rent. However, there are important exceptions. Certain business owners, employers, and specific situations may qualify for deductions. Knowing these cases helps you avoid confusion during tax season.
When Life Insurance Premiums Are Tax Deductible
Some businesses and organizations can deduct life insurance premiums. Here’s where it gets interesting:
1. Business-owned Life Insurance
When a business buys life insurance to protect itself, some premiums may be deductible. For example, if a company takes out a key person insurance policy (to protect against the loss of a vital employee), the premium is usually not deductible. But, when the business uses life insurance as part of a qualified employee benefit plan, things change.
2. Group Term Life Insurance For Employees
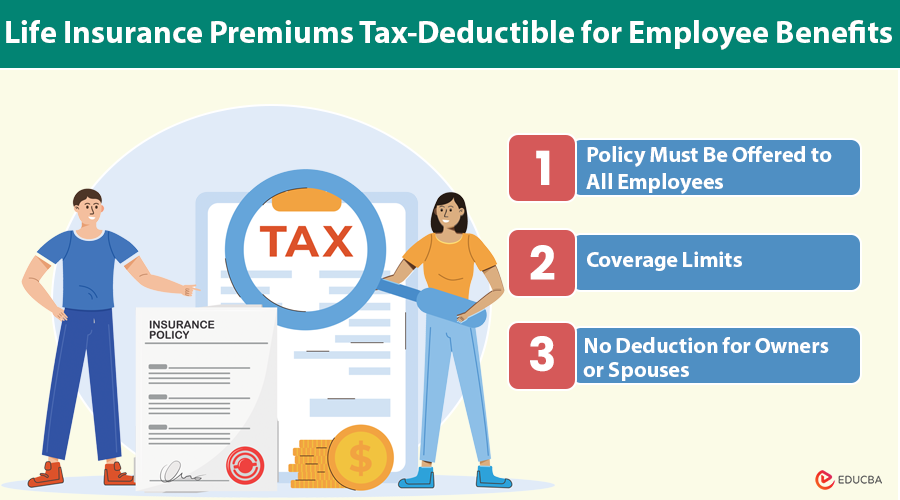
Employers often offer group term life insurance as a benefit. The IRS allows businesses to deduct premiums paid on the first $50,000 of coverage per employee. The benefit must be available to all employees, not just owners or executives.
| Type of Life Insurance | Tax Deductible? | Notes |
|---|---|---|
| Personal Policy | No | For individual or family use |
| Group Term (up to $50k) | Yes | Employer deduction allowed |
| Key Person Insurance | No | Premiums not deductible |
3. Life Insurance In Qualified Retirement Plans
Sometimes, life insurance is included in qualified retirement plans like a 401(k) or pension. In these rare cases, a part of the premiums might be deductible for the business. However, strict rules apply, and this strategy is less common today.
4. Charitable Life Insurance Donations
If you transfer ownership of a life insurance policy to a charity, you may be able to deduct the premiums as a charitable donation. The deduction equals the fair market value of the policy or the premiums paid, whichever is less. Make sure the charity is a qualified organization.

When Life Insurance Premiums Are Not Deductible
It’s easy to make mistakes with life insurance and taxes. Here are common cases where you can’t deduct premiums:
- Personal policies for yourself, your spouse, or your children
- Key person insurance when the business is also the beneficiary
- Policies used as loan collateral (unless for a deductible business loan)
- Premiums paid by S-corporations on behalf of shareholders (owners with more than 2% ownership)
Comparing Deductible Vs Non-deductible Scenarios
Seeing the difference side by side can help clarify:
| Scenario | Deductible? | Example |
|---|---|---|
| Employer-paid group term policy (up to $50,000) | Yes | Company provides basic coverage for all staff |
| Individual whole life insurance | No | Parent buys policy for family security |
| Charitable life insurance donation | Yes | Policy gifted to local nonprofit |
Practical Tips For Maximizing Tax Benefits
- Check your policy type. Group term policies often provide the best deduction opportunities for employers.
- Get professional advice. Tax laws change, and mistakes can be costly.
- Keep good records. Save all documents related to your life insurance premiums and deductions.
- Consider alternatives. Sometimes, increasing salary or offering other benefits may provide better tax results for both employer and employee.
- Review with your CPA. Especially if you’re using life insurance as part of a retirement or charitable strategy.
Common Mistakes To Avoid
Many people try to deduct life insurance premiums when they shouldn’t. Here’s what to watch for:
- Believing all business policies are deductible: Only very specific situations qualify.
- Confusing “business expense” with “tax deduction”: Not all business expenses are deductible.
- Forgetting about imputed income: For employees, coverage over $50,000 is treated as taxable income.
One insight often missed: if you receive life insurance benefits as a beneficiary, those proceeds are generally tax-free. However, if the policy was part of a group plan and exceeded $50,000, a portion may be taxable as income.
Real-world Example
Maria owns a small business and buys key person insurance for her partner. She pays $2,000 in annual premiums. Because the business is both the owner and beneficiary, the IRS does not allow her to deduct these premiums. If, instead, Maria uses the same $2,000 to offer group term life insurance to her employees (up to $50,000 each), the business can deduct those premiums as an employee benefit.
What About Life Insurance Cash Value?
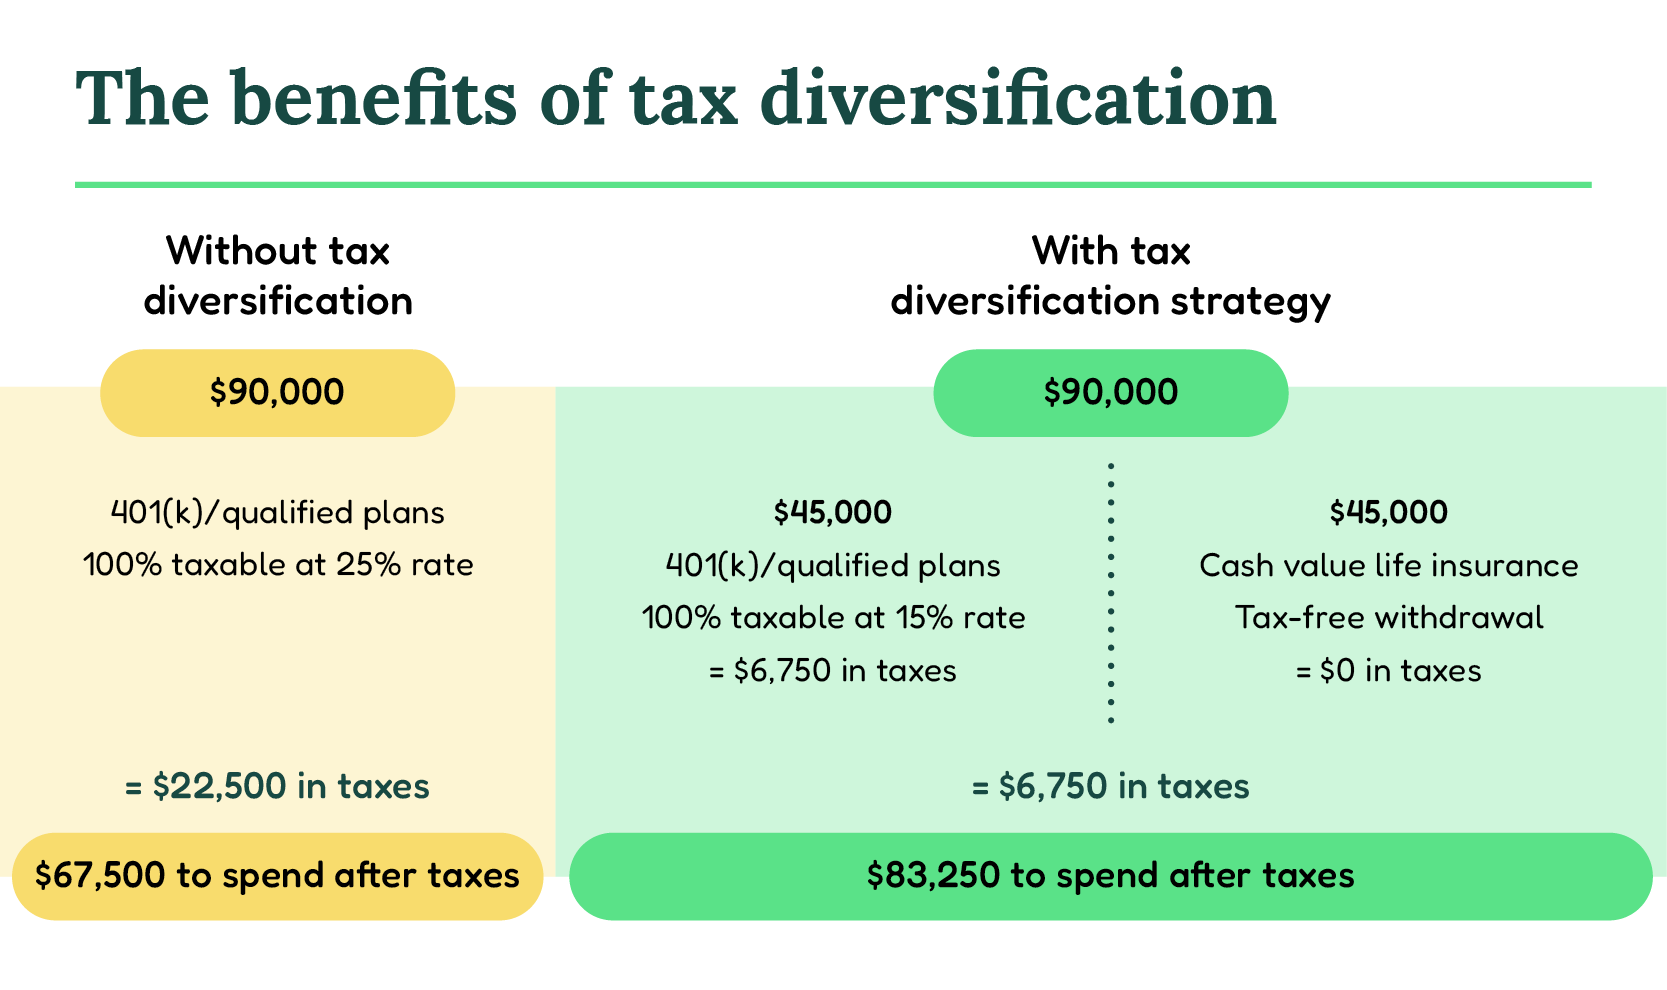
Permanent life insurance, like whole life or universal life, builds cash value over time. The premiums for these policies are also not tax deductible. However, the cash value grows tax-deferred. You don’t pay taxes on earnings until you withdraw more than you paid in.
How To Claim A Deduction (if Eligible)
If you qualify for a deduction, you’ll usually report it on your business tax return. For charitable donations, you use Schedule A when itemizing deductions on your individual tax return. Documentation is key—keep policy details, proof of payment, and any correspondence with your accountant.
Key Takeaways
- Most life insurance premiums are not tax deductible.
- Exceptions exist for group term policies, certain retirement plans, and charitable donations.
- Employers should focus on group policies for the best tax advantages.
- Individual policies for personal or family use don’t qualify.
- Always confirm with a tax professional before claiming a deduction.
For more official details, see the IRS’s guide to life insurance and taxes at IRS Publication 525.
Frequently Asked Questions
Is Life Insurance Tax Deductible For Self-employed Individuals?
No, premiums for personal life insurance are not deductible for the self-employed. Only certain business-related policies, like group term life insurance for employees, may qualify.
Are Life Insurance Death Benefits Taxable?
Usually, death benefits are tax-free for beneficiaries. However, exceptions exist if the policy was transferred for value or part of an employer group plan over $50,000.
Can I Deduct Life Insurance If It’s Required By My Lender?
No, even if a lender requires you to buy life insurance as collateral for a loan, premiums are not deductible unless the loan is for a business and the policy is business-owned.
What Is Imputed Income With Group Term Life Insurance?
Imputed income is the value of coverage over $50,000 in employer-paid group term life insurance. This extra amount is counted as taxable income for the employee.
Can I Deduct Premiums If I Give My Life Insurance Policy To Charity?
Yes, if you transfer ownership to a qualified charity, you may deduct the lesser of the premiums paid or the policy’s fair market value as a charitable donation.
Choosing the right life insurance can protect your loved ones and, in some cases, lower your tax bill. But the rules are specific, and mistakes are common. When in doubt, check with a qualified tax advisor to keep your finances safe.