
Deciding between life insurance and mortgage protection is not always easy. Many people who buy a house or start a family wonder which option is best. Both help protect your loved ones if something happens to you, but they are not the same. Picking the right one can save you money, reduce stress, and make sure your family is safe. This article will help you understand both types, compare them, and show you what really matters for your situation. If you are new to insurance, don’t worry—everything is explained simply, with clear examples and facts. By the end, you’ll know which is better for you: life insurance or mortgage protection.
What Is Life Insurance?
Life insurance is a contract between you and an insurance company. You pay a set amount each month or year (called a premium). If you die while the policy is active, the insurance company pays money to your chosen person (called a beneficiary). This money is called the death benefit.

Life insurance comes in different types. The most common are:
- Term life insurance: Lasts for a set period (like 10, 20, or 30 years). If you die during this time, your family gets paid. If you live past the term, the policy ends.
- Whole life insurance: Lasts your whole life. It costs more but builds up cash value you can use while alive.
The death benefit is usually paid in one lump sum. Your beneficiary can use the money for anything: paying debts, living costs, funeral expenses, or children’s education.
Example
Imagine you buy a $500,000 term life insurance for 20 years. If you die during that time, your family gets $500,000. If you live, nothing is paid out, and the policy ends after 20 years.
Key Benefits
- Flexible use: The payout can be used for any purpose.
- Protects your family: Helps them cover living costs if you are gone.
- Can cover large debts: Useful if you have loans, like a mortgage.
What Is Mortgage Protection Insurance?
Mortgage protection insurance is a special type of life insurance. It is designed only to pay off your mortgage if you die. The payout goes directly to the mortgage lender, not your family.
This insurance is usually for the same length as your mortgage (like 20 or 30 years). The amount paid out reduces over time, because as you pay your mortgage, the remaining debt goes down.
Example
You buy mortgage protection for a $300,000 mortgage. If you die, the insurer pays the remaining mortgage to your lender. Your family keeps the house but does not get any extra money.
Key Benefits
- Pays off your home loan: Your family won’t lose the house if you die.
- Automatic payout: Goes straight to the lender, removing stress for your loved ones.
- Simple to set up: Often sold when you buy your mortgage.
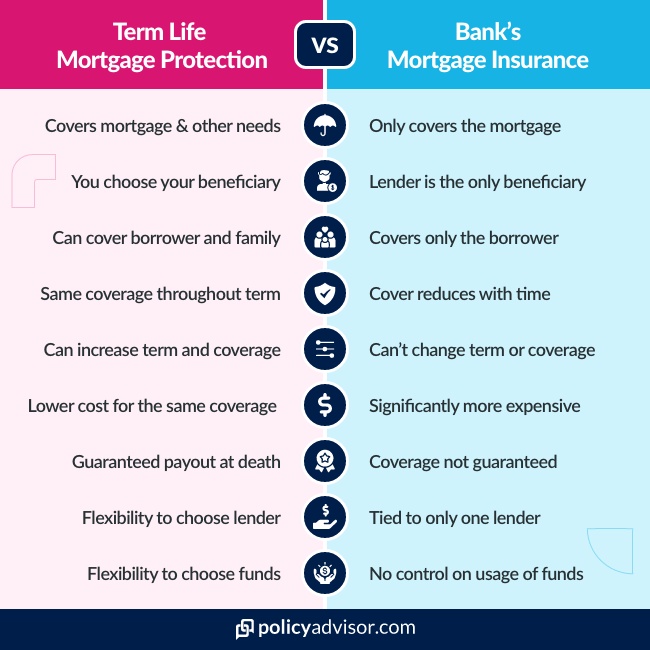
Key Differences Between Life Insurance And Mortgage Protection
Understanding how these two types differ is important. Here are the main differences:
| Feature | Life Insurance | Mortgage Protection Insurance |
|---|---|---|
| Payout Use | Flexible (any purpose) | Only pays off mortgage |
| Beneficiary | Family or chosen person | Mortgage lender |
| Payout Amount | Fixed | Decreases over time |
| Policy Length | Flexible | Matches mortgage term |
| Cost | Can be higher or lower | Usually lower |
Life insurance gives your family freedom to use the money as they need. Mortgage protection is more limited—it simply pays off your home loan.
Cost Comparison
People often ask which is cheaper. The answer depends on your age, health, and how much coverage you want. But in general, mortgage protection is often less expensive because the payout gets smaller over time.
Here is a simple cost comparison:
| Policy Type | Sample Monthly Cost (Age 35, Non-smoker) | Coverage Amount | Term Length |
|---|---|---|---|
| Term Life Insurance | $35 | $300,000 | 20 years |
| Mortgage Protection Insurance | $22 | $300,000 (decreases) | 20 years |
*These are average US costs as of 2024. Your price may be higher or lower. *
Which Is Better For You?
Choosing between life insurance and mortgage protection depends on your needs. Let’s look at different situations.
If You Have A Family
If you have a spouse or children who depend on your income, life insurance is usually better. It gives them money to pay for more than just the house—like food, bills, and school. They decide how to use the money.
If You Are Single With No Dependents
If you live alone and only want to protect your home, mortgage protection may be enough. It will pay off your mortgage so no one has to worry about selling the house if you die.
If You Want Flexibility
Life insurance offers more flexibility. You can cover your mortgage and other debts. Your family can use the payout for whatever they need.
If You Only Want To Protect Your Home
Mortgage protection is simple and straightforward. It makes sure your house is paid off, but your family does not get extra money.
Common Mistakes Beginners Make
Many people make mistakes when choosing insurance. Here are a few to watch out for:
- Thinking mortgage protection covers all needs: It only pays the mortgage. If your family needs money for other things, it’s not enough.
- Not considering future changes: Your needs may change. Children, new debts, or job loss can affect what you need.
- Choosing based only on price: Cheaper is not always better. Look at what is covered.
- Ignoring health questions: Some policies ask about health. If you lie or miss details, your claim may be denied.
- Not reviewing policies regularly: As life changes, your insurance should change too.

Real-life Examples
Let’s see how this works in real life.
- Sarah and David: They have two kids and a $250,000 mortgage. David buys term life insurance for $500,000. If he dies, his family can pay off the house and have extra money to live on.
- Lisa: She is single, owns a condo, and has a $120,000 mortgage. She chooses mortgage protection. If she dies, the condo is paid off and goes to her parents.
Notice how Sarah and David’s choice gives more security to their family. Lisa’s choice is simple and meets her needs.
Non-obvious Insights
Most beginners do not realize:
- Life insurance can cover more than just your mortgage. It can help with medical bills, student loans, or lost income.
- Mortgage protection often does not cover critical illness or disability. If you get sick or cannot work, your mortgage protection may not pay. Some life insurance policies include extra coverage for illness or disability.
How To Decide: Step-by-step
Here’s a simple way to choose:
- List your debts: Write down your mortgage, loans, and other big bills.
- Think about your family: Do others depend on your income? If yes, life insurance is usually better.
- Check your budget: Find out what you can afford each month.
- Compare policies: Look at both options. Check what is covered, who gets the payout, and how much.
- Ask questions: Talk to an insurance agent or do research online.
- Read the fine print: Make sure you understand what is included and what is not.
What Experts Recommend
Most financial experts say life insurance is better for families or anyone with people who depend on them. It offers more coverage and flexibility. Mortgage protection is best for those who only need to pay off their house.
A survey by the Insurance Information Institute found that 60% of US households rely on life insurance to cover more than just their mortgage. Only 15% use mortgage protection alone.
Pros And Cons
Here is a quick look at the main pros and cons.
| Type | Pros | Cons |
|---|---|---|
| Life Insurance | – Flexible payout – Covers more needs – Can include extra benefits |
– Can cost more – Needs regular review – More paperwork |
| Mortgage Protection | – Simple – Usually cheaper – Easy to set up |
– Limited payout – Only covers mortgage – No extra money for family |
Practical Tips For Choosing
- Don’t rush. Take time to compare.
- Get quotes from different companies.
- Check reviews of insurance providers.
- Ask about extra benefits like critical illness cover.
- Update your policy if your life changes (marriage, children, new debts).
If you want more detailed numbers and studies about insurance, visit Insurance Information Institute.
Frequently Asked Questions
What Happens If I Outlive My Mortgage Protection Policy?
If you finish paying your mortgage before the policy ends, the coverage stops. You do not get any money back. It only pays if you die while you still owe money.
Can I Use Life Insurance Payout To Pay Off My Mortgage?
Yes, your family can use the life insurance payout for the mortgage or anything else they need. The money goes to your chosen beneficiary, not the lender.
Is Mortgage Protection The Same As Life Insurance?
No. Mortgage protection is a type of life insurance, but it only pays off your mortgage. Regular life insurance covers more needs and gives the payout to your family.
How Do I Know How Much Coverage I Need?
Add up your debts, living costs, and any money your family will need if you are gone. Many experts suggest life insurance that is 7-10 times your yearly income.
Can I Have Both Life Insurance And Mortgage Protection?
Yes, you can have both. Some people use mortgage protection for their house and life insurance for other needs. But often, life insurance alone is enough.
Choosing between life insurance and mortgage protection is about understanding your needs. For most families, life insurance offers more security and flexibility. If you only want to protect your home, mortgage protection can be a simple solution. Take time to compare, ask questions, and review your options. Making the right choice will help your loved ones feel safe and supported—no matter what happens.