
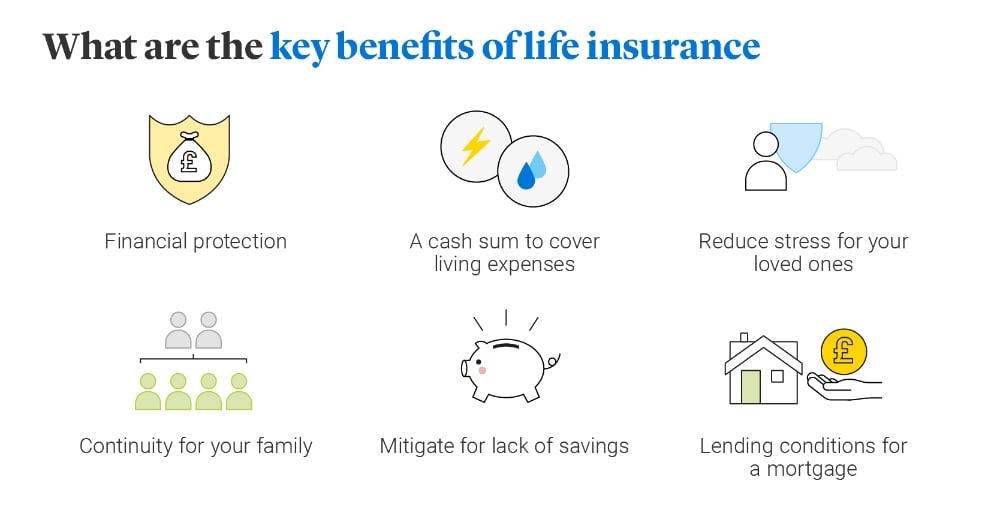
Life insurance is often seen as something that only helps your family after you pass away. But many people in the UK do not realize that you can actually use your life insurance policy while you are still alive. This can offer financial support in tough situations, fund important life events, or even help you plan for retirement. Knowing how to access these benefits can make a real difference in your financial security and peace of mind.
This guide explains the ways you can use life insurance while alive in the UK. Whether you want to unlock cash from your policy, pay for urgent medical care, or boost your pension, understanding your options can give you more control over your money.

Many people miss valuable opportunities simply because they do not know what is possible. Let’s explore how you can make your life insurance work for you today—not just for your loved ones in the future.
How Life Insurance Works In The Uk
Before looking at how to use life insurance while alive, it’s important to know the basics. In the UK, life insurance is a contract between you and an insurance company. You pay a regular premium, and the insurer promises to pay a lump sum if you die during the policy term. Some policies also cover critical illness or permanent disability.
There are two main types:
- Term life insurance: Covers you for a set period (e.g., 20 years). If you die during this time, your family gets a payout.
- Whole-of-life insurance: Covers you for your entire life. The payout is guaranteed, as long as you keep paying premiums.
Some policies include extra features or riders that let you access money early under certain conditions. Understanding the type of policy you have is key to knowing what you can do with it while you are still alive.
Ways To Use Life Insurance While Alive
Many people think life insurance is only for after death, but there are several ways to benefit during your lifetime. Here are the main options available in the UK:
1. Critical Illness Cover
Many UK life insurance policies include critical illness cover or offer it as an add-on. If you are diagnosed with a serious illness (like cancer, stroke, or heart attack), you may be able to claim part or all of your policy’s value while you are alive.
For example, if you have a £200,000 life insurance policy with critical illness cover, and you are diagnosed with a covered illness, you could receive a lump sum to help with medical bills, living expenses, or home modifications. This means you get financial support when you need it most.
Non-obvious insight: Some policies only pay out once—so if you claim for a critical illness, there may be no payout left for your family after your death. Always check the terms.
2. Terminal Illness Benefit
Most modern UK life insurance policies include a terminal illness benefit. If you are diagnosed with a terminal illness (a doctor believes you have less than 12 months to live), you can usually claim the full payout early.
This money can help you:
- Pay for care and support
- Settle debts
- Make special memories with loved ones
The key difference from critical illness cover is that terminal illness benefit is only paid if your life expectancy is less than a year.
3. Cash Value Withdrawal (whole-of-life And Investment-linked Policies)
Some types of life insurance, like whole-of-life or investment-linked policies (e.g., with-profits or unit-linked policies), build up a cash value over time. This means a portion of your premium is invested, and the policy grows in value.
You can sometimes:
- Withdraw cash: Take out a portion of the cash value. This reduces the final payout but gives you money to use now.
- Take a loan: Borrow against the policy’s cash value, paying interest but keeping the policy in force.
Example: If your whole-of-life policy has a cash value of £30,000, you may be able to withdraw or borrow up to this amount, depending on the insurer’s rules.
Non-obvious insight: Withdrawing cash or taking a loan may reduce the final payout or even cause the policy to lapse if not managed carefully.
4. Surrendering The Policy
If you no longer need the cover or cannot afford the premiums, you can surrender your whole-of-life or investment-linked policy. The insurer will pay you the surrender value, which is often less than the total premiums you have paid, but it gives you access to a lump sum now.
- Term life policies usually do not have surrender value.
- Whole-of-life and endowment policies may have surrender value after a certain period.
5. Life Insurance Trusts And Early Payouts
Setting up your policy in a trust can sometimes help you access money faster if you become seriously ill. While trusts are mainly for estate planning, some advanced trust structures allow for early payouts in certain situations, giving you or your family quick access to funds.
Practical example: If you put your policy in a trust for “serious illness,” the trustees might be able to release funds quickly if you need urgent care.
Comparing Main Ways To Access Life Insurance While Alive
Here is a quick comparison to help you see the main differences between the options:
| Option | Who Qualifies | How Much Can You Get? | Impact on Death Payout |
|---|---|---|---|
| Critical Illness Cover | Diagnosed with covered illness | All or part of sum assured | May reduce or use up death payout |
| Terminal Illness Benefit | Terminal diagnosis (<12 months) | Full sum assured | No payout after death (already paid) |
| Cash Value Withdrawal | Whole-of-life/investment policyholders | Up to cash value amount | Death payout reduced accordingly |
| Surrender Value | Whole-of-life/investment policyholders | Surrender value (varies) | Policy ends, no death payout |
Using Life Insurance For Retirement Or Major Life Events
Some people use the cash value in their life insurance to fund retirement or big life events, like children’s education or starting a business. This is more common with whole-of-life or investment-linked policies.
How It Works
- Over many years, your policy builds up a cash value.
- At retirement, you can withdraw money or take a loan.
- This can help supplement your pension or pay for large expenses.
Important: Withdrawing too much can reduce your family’s protection or even cancel the policy. Always check with a financial adviser.
Real-world Example
Sarah, age 60, has a with-profits whole-of-life policy worth £40,000 in cash value. She decides to withdraw £10,000 to help her daughter start a business. Her future death payout is reduced by this amount, but she uses the money now for something important.
Policy Loans: Borrowing Against Your Life Insurance
Some life insurance policies let you borrow money using your policy as security. This is called a policy loan.
- You borrow up to a certain percentage of the policy’s cash value.
- Interest is charged, but you do not need to pass a credit check.
- If you do not repay, the loan (plus interest) is deducted from the death payout.
Practical tip: Policy loans can be a quick way to access cash in an emergency, but the interest may be higher than a personal loan. Make sure you understand the costs.
Selling Or Transferring Your Policy (life Settlements)
In the US, people can sell their life insurance policies for cash (called a life settlement). In the UK, this option is less common, but some endowment policies can be sold to specialist companies or investors.
- The buyer pays you a lump sum (usually more than surrender value but less than the full payout).
- The buyer takes over the premiums and gets the payout when you die.
This can be an option if you have an old endowment policy and need cash now.
How To Access Money From Your Policy: Step-by-step
If you want to use your life insurance while alive, here is how to get started:
- Check your policy type and terms: See if you have term, whole-of-life, or investment-linked cover.
- Review benefits and riders: Look for critical illness, terminal illness, cash value, or surrender options.
- Contact your insurer: Ask for a policy statement and discuss available options.
- Get advice: Consider speaking to a regulated financial adviser to understand tax implications and long-term impact.
- Make a claim or request: Follow the insurer’s process for withdrawals, loans, or early payouts.
Common mistake: Many people do not realize that cash withdrawals or loans may have tax consequences. Ask your adviser or insurer about possible taxes before making a decision.
Comparing Policy Features: Term Vs. Whole-of-life
To understand which policies offer the most flexibility, compare basic features:
| Feature | Term Life Insurance | Whole-of-Life Insurance |
|---|---|---|
| Cash Value | No | Yes, builds over time |
| Critical Illness Option | Often available as add-on | Often included or optional |
| Policy Loans | No | Yes |
| Surrender Value | No | Yes |
| Premiums | Usually lower | Usually higher |
Key takeaway: If you want to use your policy while alive, whole-of-life or investment-linked policies offer more options than simple term policies.
Tax Considerations
Accessing money from your life insurance policy can have tax consequences:
- Critical or terminal illness payouts are usually tax-free.
- Withdrawals or loans from cash value may have income tax implications, especially if you withdraw more than you paid in.
- Surrender value may be subject to tax, depending on the gain.
Always check with a tax adviser before withdrawing money from your policy.
Choosing The Right Policy For Flexibility
If you are buying new life insurance and want the option to use it while alive, consider:
- Whole-of-life policies for cash value and flexibility
- Adding critical illness cover for early payouts
- Looking for policies with policy loan features
Compare the costs and benefits carefully. Do not choose extra features you do not need, as they will increase your premium.
Common Mistakes To Avoid
- Not checking policy features: Many people do not know what their policy allows. Always read your documents and ask questions.
- Withdrawing too much cash: Taking out too much can leave your family with little or no payout after you are gone.
- Ignoring tax consequences: Some withdrawals are taxable; check before you act.
- Letting the policy lapse: If you stop paying premiums after withdrawing cash, your policy may end and you could lose all benefits.
- Not getting advice: Life insurance is complex; professional advice can help you avoid expensive mistakes.
When Using Life Insurance While Alive Makes Sense
Accessing your life insurance while alive can be a smart move if:
- You face a serious illness and need funds urgently
- You want to support retirement income or major life events
- You have a cash value policy and need liquidity
But it is not right for everyone. If your main goal is to protect your family, consider the impact on the future payout before acting.
Where To Get More Information
For detailed information on UK life insurance options, the MoneyHelper website is a trusted source: MoneyHelper. It offers clear guides and tools to help you compare policies and make informed decisions.
Frequently Asked Questions
What Types Of Life Insurance Let Me Access Money While Alive?
Whole-of-life and investment-linked policies usually let you withdraw cash or take loans. Some term policies offer critical or terminal illness payouts. Check your policy documents for details.
Is Early Payout From Life Insurance Taxable In The Uk?
Critical or terminal illness payouts are usually tax-free. Withdrawals or loans from cash value may be taxable if there is a gain. Always seek tax advice.
Can I Borrow Money From My Life Insurance Policy?
Yes, some whole-of-life or endowment policies allow policy loans. You borrow against the cash value and repay with interest. Not all insurers offer this.
What Happens If I Surrender My Policy?
If you surrender a cash value policy, you get a lump sum (the surrender value), but your cover ends and no payout is made after your death.
Does Using Life Insurance While Alive Affect My Family’s Payout?
Yes. Withdrawing cash, taking a loan, or claiming for critical illness usually reduces the amount paid out after your death, or may cancel the policy.
Using your life insurance while you are alive can bring major benefits—but it’s important to understand your policy, weigh the pros and cons, and get advice before making changes. With the right approach, your policy can give you peace of mind now, as well as in the future.