
Life insurance is a simple idea: people pay premiums to protect their loved ones if something happens to them. But behind this, life insurance companies run a complex business. Many people wonder, “Where do life insurance companies make money?” The answer is not as simple as collecting payments and paying claims. These companies use clever strategies, smart investments, and risk management to stay profitable. In this article, you’ll discover the main ways life insurance companies make money, with real examples, data, and easy explanations.
Premiums: The Foundation Of Revenue
Life insurance companies earn most of their income from policy premiums. When you buy life insurance, you pay a set amount (monthly or yearly) to the insurer. This is called a premium. The company collects premiums from thousands or millions of customers. These payments make up their primary revenue stream.

For example, in 2022, U.S. life insurers collected over $600 billion in premiums. But they don’t simply keep all this money. Part of it is used to pay claims when a policyholder dies, while the rest is managed for profit.
Some key points about premiums:
- Companies use actuarial science to set the right premium price based on risk.
- If premiums are too low, they risk losing money. If too high, they lose customers.
- Not every policyholder claims their policy, so companies keep the difference.
Many beginners think companies only make money when people don’t claim their policy. This is only partly true. Most life insurance policies are designed so the company expects to pay out eventually, especially for whole life or endowment plans. The real profit comes from how they manage the money collected.
Investment Income: Making Money Work
Life insurance companies invest the premiums they collect. This is where they make much of their profit. After setting aside enough money for future claims (called reserves), they invest the rest in assets like bonds, stocks, real estate, and government securities.
Let’s look at how this works:
| Asset Type | Average Percentage of Portfolio | Typical Return Rate |
|---|---|---|
| Bonds | 60% | 3-5% |
| Stocks | 15% | 7-10% |
| Real Estate | 10% | 5-8% |
| Cash & Short-Term | 15% | 1-2% |
Insurance companies must be careful with investments. They need enough safe assets to pay claims at any time. That’s why most portfolios are heavy in bonds and low-risk securities. In 2023, U.S. life insurers earned about $250 billion from investment income.
A non-obvious insight: Companies can earn more from investments than from premiums alone. For example, if a company collects $1 billion in premiums and invests at 5% annual return, it earns $50 million extra each year, which boosts profits even if claims are paid out.
Underwriting: Risk Selection And Pricing
Underwriting is a process where the company decides who gets insurance and at what price. It’s a key profit driver because the company must balance risk and reward.
Here’s how underwriting helps companies make money:
- Assess Risk: The company checks the applicant’s age, health, lifestyle, and family history.
- Price Premiums: Riskier applicants pay higher premiums. Healthy people pay less.
- Avoid High-Risk Policies: If someone is too risky (bad health, dangerous job), the company may decline the policy.
Underwriting is not just about avoiding losses. It’s also about finding the right price so the company can profit over time. Many beginners miss that underwriting is a skillful balancing act. Companies use data, medical tests, and statistics to get this right.
Policy Lapses And Cancellations
Another hidden profit source is policy lapses. Many people buy life insurance but stop paying after a few years. When a policy lapses, the company keeps the premiums paid so far, but does not have to pay a death claim.
For example, in the U.S., about 20% of life insurance policies lapse each year. This means millions of dollars collected without having to pay out.
Some policies, like term life insurance, are more likely to lapse because they have no cash value. Companies factor this into their pricing. It’s a subtle but important way insurers boost profits.
Fees And Charges: Additional Revenue Streams
Life insurance policies often include extra fees and charges. These are not always obvious to buyers but add to the company’s income.
Common fees include:
- Policy administration fees: For managing the policy.
- Rider fees: Extra coverage, like accidental death or disability.
- Surrender charges: For early withdrawal from cash-value policies.
- Loan interest: If the policyholder borrows against the policy.
For example, in variable universal life policies, fees can add up to 2-3% per year. This may not sound like much, but across thousands of policies, it adds significant revenue.
A practical tip: Always check the policy’s fee structure before buying. Hidden charges can reduce your investment returns or cash value.
Reinsurance: Managing Large Risks
Life insurance companies use reinsurance to protect themselves from big losses. Reinsurance means the company buys insurance from another insurer (a reinsurer) to cover part of its risk.
How Does This Help Make Money?
- It lets companies take on more policies safely.
- They can write large-value policies without fear of huge losses.
- Reinsurers take a share of the premiums, but the original insurer keeps some profit.
For example, if a company sells a $10 million policy, it may keep $2 million risk and transfer $8 million to a reinsurer. This way, the company earns revenue from many policies while staying protected.
Cash Value Policies: Investment And Interest Earnings
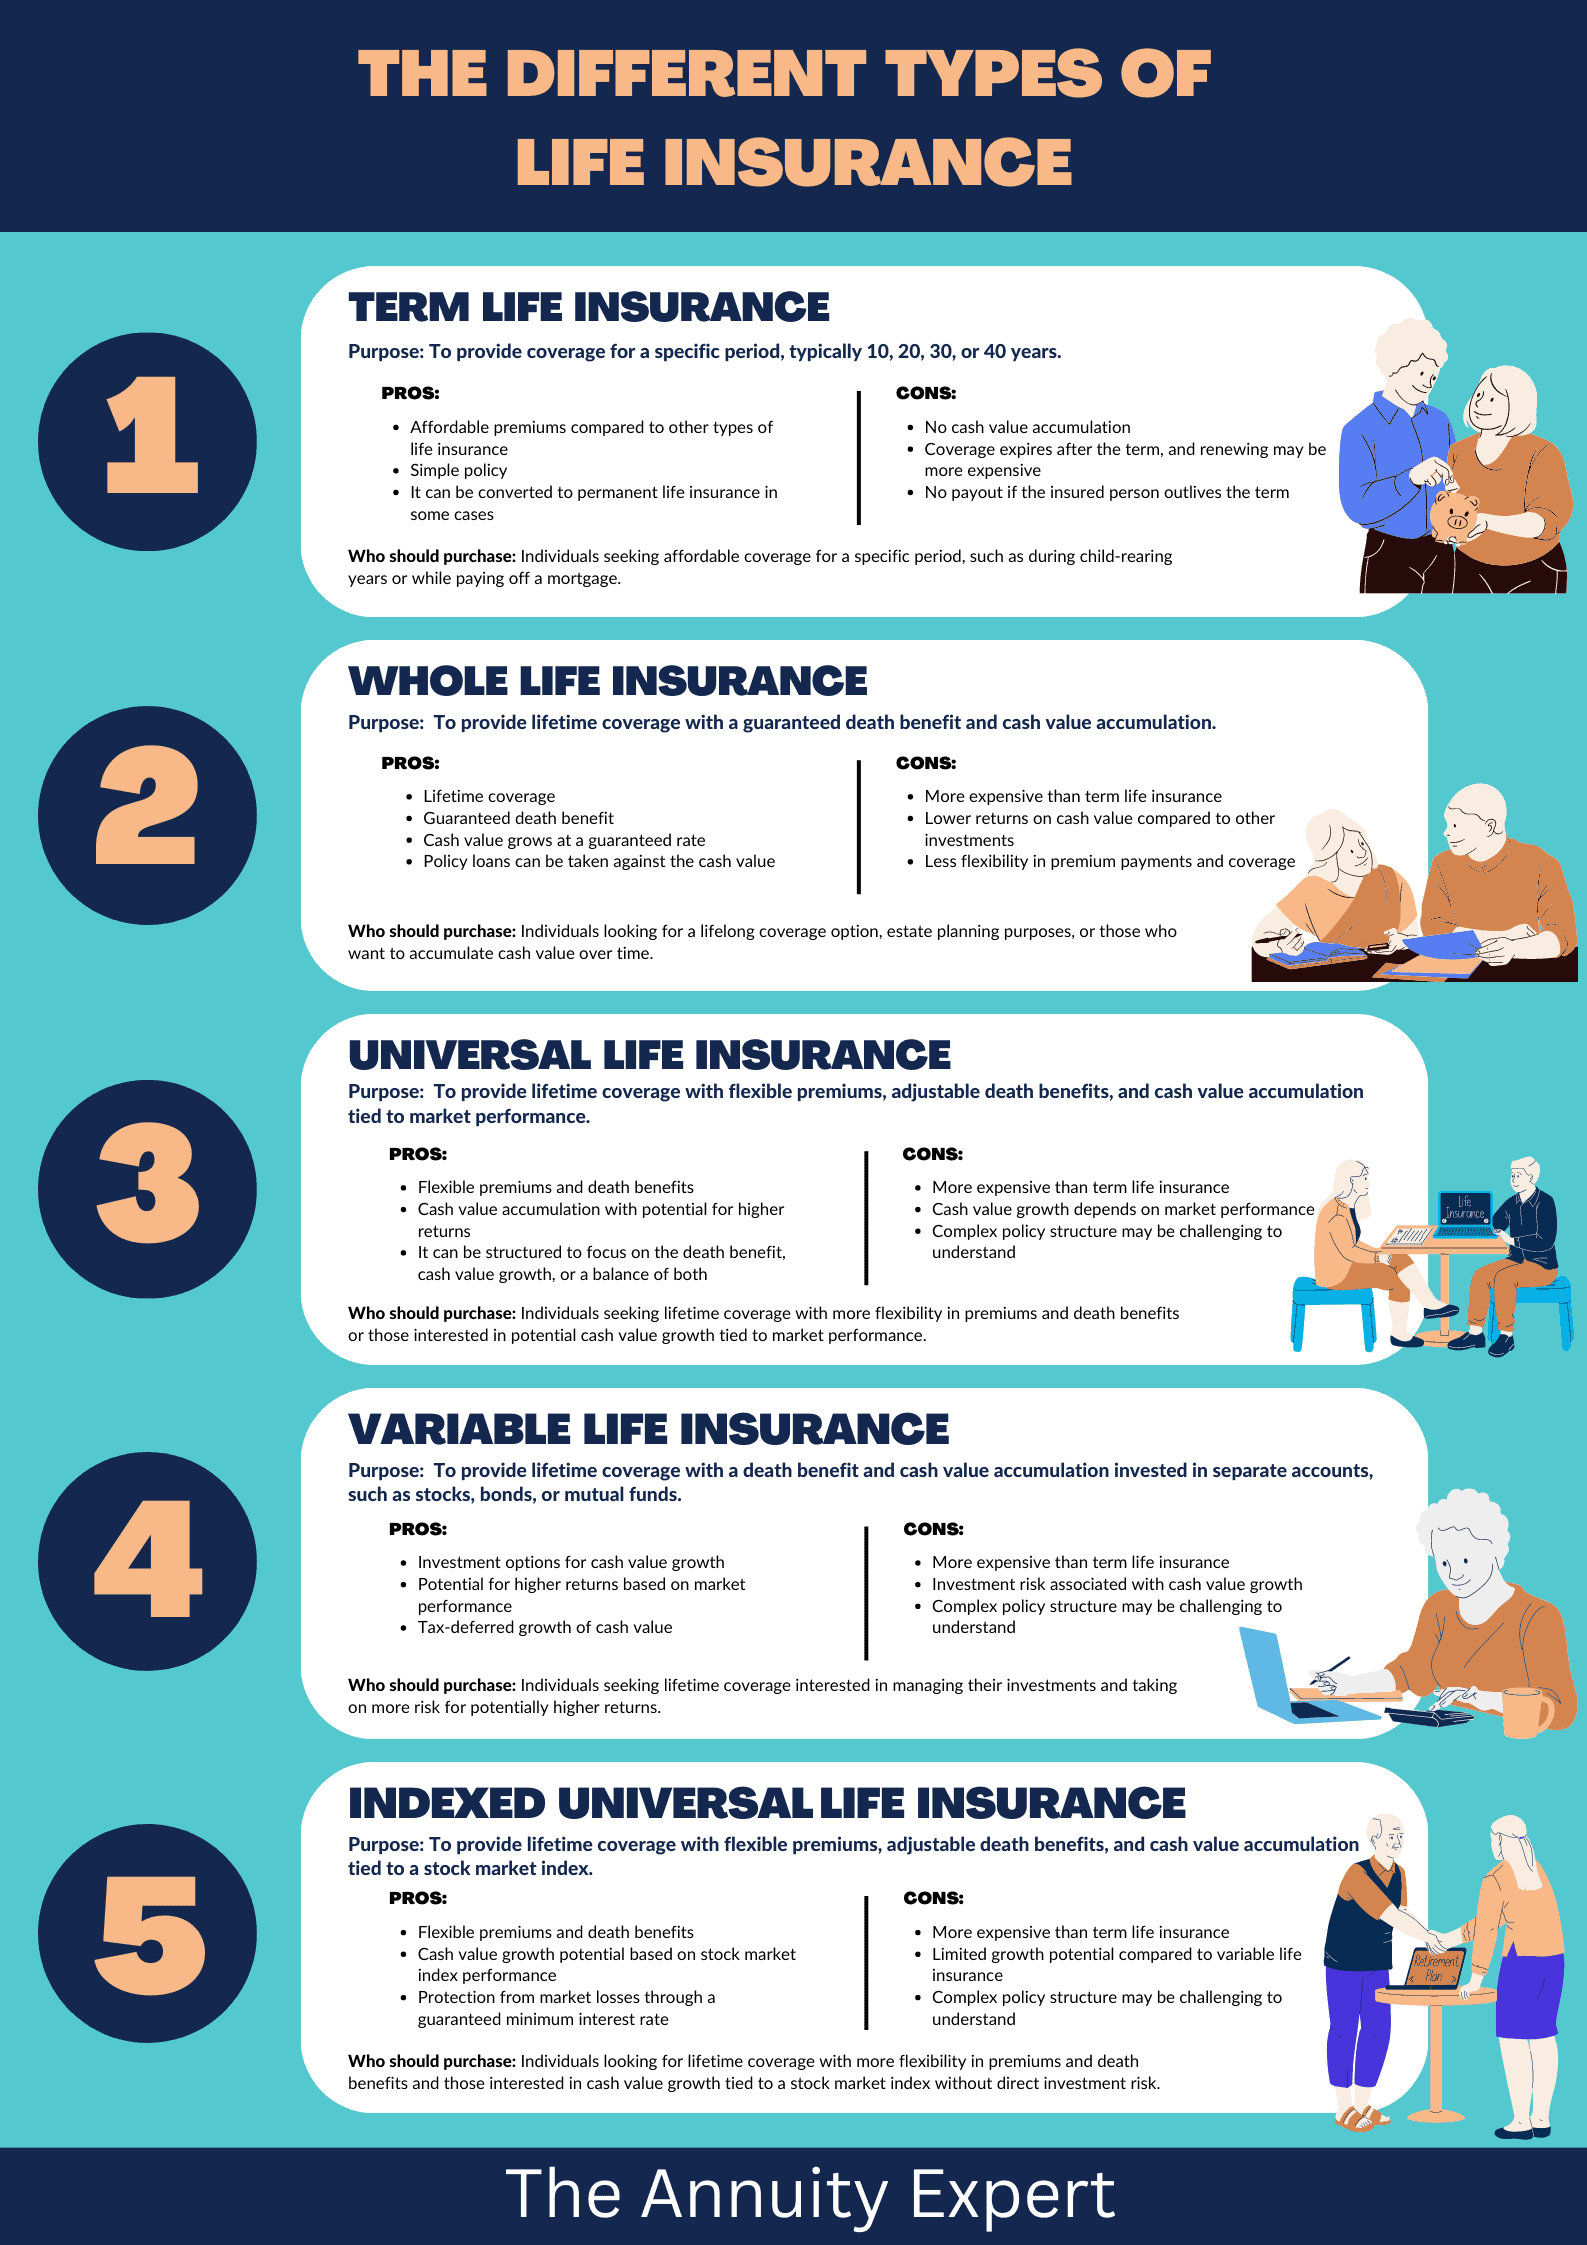
Some life insurance policies, like whole life or universal life, have a cash value component. Part of your premium goes into a savings or investment account. The company invests this money and credits you with interest or investment returns.
But here’s the catch: The company often earns a higher return than it pays you. For example, if the company invests at 6% but credits your policy at 3%, it keeps the difference (called the “spread”). This is a steady source of profit.
Let’s compare cash value growth:
| Year | Premium Paid | Cash Value Credited | Company Investment Earnings |
|---|---|---|---|
| 1 | $5,000 | $1,500 | $2,000 |
| 5 | $25,000 | $10,000 | $12,500 |
| 10 | $50,000 | $25,000 | $30,000 |
As you can see, the company keeps a portion of investment returns. This “interest spread” is a major profit source for cash value policies.
Expense Management: Efficiency Matters
Profit is not just about earning more. It’s also about spending less. Life insurance companies work hard to control expenses like salaries, technology, marketing, and claims processing.
Efficient companies use:
- Automated systems to handle applications and claims
- Data analytics to detect fraud and errors
- Cost-saving partnerships with reinsurers
For example, a company with lower expense ratios (costs as a percentage of premiums) can offer better prices and still make money. Industry average expense ratios are about 10-15%. Top companies aim for lower rates to stay competitive.
A beginner mistake is to ignore expenses. Profit comes from both revenue and cost control.
Market Expansion And Product Innovation
Insurance companies also make money by expanding into new markets and launching innovative products. They may target younger customers, offer online policies, or design flexible coverage options.
Some trends include:
- Selling through digital channels (apps, websites)
- Offering “micro-insurance” for small amounts
- Bundling insurance with other financial products
Innovation helps companies reach more customers and earn new revenue. For example, online sales grew by 30% in the U.S. between 2020 and 2023.
Comparison: Life Insurance Vs. Other Insurance Companies
Life insurance companies have different profit models compared to other insurers (like auto or health). Here’s a quick comparison:
| Type | Main Revenue Source | Claims Frequency | Investment Strategy |
|---|---|---|---|
| Life Insurance | Premiums & Investment | Low (long-term) | Long-term, stable assets |
| Health Insurance | Premiums & Fees | High (frequent claims) | Short-term, liquid assets |
| Auto Insurance | Premiums | Medium (accidents) | Mix of assets |
Life insurance relies more on long-term investments and careful pricing, while health or auto insurance deals with frequent claims and short-term asset management.
Real-world Example: Prudential Financial
To see these strategies in action, let’s look at Prudential Financial, one of the largest U.S. life insurers.
- In 2022, Prudential collected over $40 billion in premiums.
- Investment income was about $15 billion.
- Prudential uses a mix of bonds, stocks, and real estate for stable returns.
- It offers many types of policies, including cash value and term life.
- Efficient expense management helps Prudential stay competitive.
Prudential’s financial reports show that investment returns often exceed what they pay out in claims. This is a classic example of how life insurance companies profit.
Non-obvious Insights For Beginners
- Profit comes from timing: Life insurers collect premiums for many years before paying claims. They invest this money, earning interest and returns, which adds to profit.
- Policy design matters: Not all policies are equally profitable. Cash value policies give more investment opportunity, but also more risk. Term policies are cheaper to manage but rely on lapses and cancellations.
Many people miss these points and think profit only comes from “not paying out claims. ” The real answer is more complex.
Frequently Asked Questions
How Do Life Insurance Companies Use Premiums To Make Money?
They collect premiums, use some to pay claims, and invest the rest. The investment returns are a major profit source. They also keep premiums from policies that lapse or are canceled.
Why Don’t Companies Lose Money When People Die?
Companies use actuarial science to predict the average number of claims. They set premiums high enough to cover payouts, expenses, and profit. They also invest premiums for extra earnings.
What Happens To Money From Lapsed Policies?
If a policyholder stops paying and the policy lapses, the company keeps all premiums paid up to that point. No claim is paid, so this becomes pure profit.
Are Cash Value Policies More Profitable For Insurers?
Yes, because insurers earn an “interest spread” by investing cash value funds at a higher rate than they credit to policyholders. This difference adds to their profits.
Is Investing Risky For Life Insurance Companies?
They choose safe, long-term assets like government bonds and high-grade corporate bonds. This lowers risk. Regulations require them to keep enough reserves to pay claims, making their investments safer than most banks or mutual funds.
Life insurance companies have many ways to make money. From collecting premiums and investing funds, to managing risk and designing smart policies, they use a mix of strategies to stay profitable. Understanding these methods can help you make smarter choices when buying insurance. For more details on the industry, visit the Insurance Information Institute for reliable facts and deeper insights.