
Choosing life insurance for your child is a decision that often brings mixed feelings. You want to protect your family, but you also want to make smart choices with your money. Many parents wonder, “How much life insurance should I get for my child?
” This question is more important than it may seem at first. The right coverage can help your family through difficult times, but too much can be unnecessary.

Let’s explore the reasons people buy life insurance for children, how to decide on the right amount, what factors to consider, and common mistakes to avoid. By the end of this article, you’ll have a clear idea of what works best for your situation.
Why Consider Life Insurance For A Child?
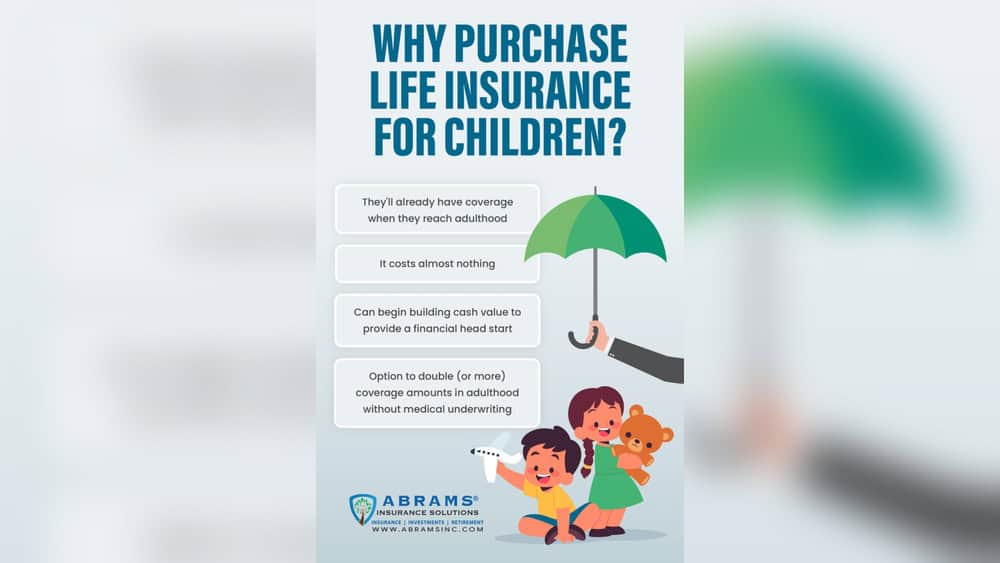
Parents usually buy child life insurance for two main reasons. First, it provides financial help if the worst happens. Second, it can protect your child’s future insurability, meaning your child can get more insurance later, even if their health changes.
Many people don’t realize that funeral costs can be high. In the US, the average funeral costs between $7,000 and $12,000. Some families may also need time off work to grieve, adding to the financial burden. A child’s life insurance policy helps cover these costs so parents can focus on their family.
Another reason is to lock in future insurability. Some policies let your child keep the insurance as an adult, even if they develop health problems later. This can be a valuable safety net.
How Much Life Insurance Is Typical For A Child?
Most child life insurance policies offer coverage between $10,000 and $50,000. This amount is usually enough to cover funeral costs and some extra expenses. Some parents choose higher amounts, up to $100,000, but this is less common.
Here is a quick look at typical coverage amounts and what they cover:
| Coverage Amount | What It Covers | Typical Monthly Cost |
|---|---|---|
| $10,000 | Basic funeral costs | $3–$5 |
| $25,000 | Funeral + short-term bills | $6–$10 |
| $50,000 | Funeral + family support | $10–$18 |
| $100,000 | Funeral + long-term support | $20–$35 |
Most experts suggest $10,000 to $25,000 is enough for most families. This covers funeral expenses and gives a little financial cushion.

Factors To Consider When Deciding The Amount
Choosing the right amount is personal. Here’s what you should think about before buying:
1. Funeral And Final Expenses
Estimate the cost of a funeral in your area. Don’t forget extra expenses like travel or time off work.
2. Family Support Needs
Would you need extra money for counseling, lost income, or other costs?
3. Your Budget
Make sure the monthly cost fits your family’s finances. Child life insurance is usually cheap, but it’s still an extra bill.
4. Future Insurability
Some policies let your child buy more insurance as an adult without a health check. If this is important, choose a policy that includes this feature.
5. Other Savings Or Life Insurance
If you already have emergency savings or other life insurance, you might not need as much coverage for your child.
Types Of Child Life Insurance
There are two main types of life insurance for children: child term riders and standalone child whole life policies.
Child Term Riders
A term rider is an add-on to a parent’s own life insurance. It’s usually cheap and covers all children in the family. When the child becomes an adult, the coverage often ends, but some plans let them convert to their own policy.
Standalone Whole Life Policies
These policies are bought just for the child. They build cash value over time. This means the policy can be worth money if you surrender it later. Premiums are fixed for life, and the child can keep the policy as an adult.
Here’s a comparison of the two types:
| Feature | Child Term Rider | Child Whole Life |
|---|---|---|
| Coverage Length | Until age 18–25 | Lifetime |
| Builds Cash Value | No | Yes |
| Can Convert to Adult Policy | Sometimes | Yes |
| Monthly Cost | $2–$7 | $5–$20 |
| Covers All Kids | Yes | No |
Non-obvious insight: Many parents don’t realize that term riders are much cheaper and simpler if you have more than one child.

How To Calculate The Right Coverage
Here’s a simple way to estimate the amount you might need:
1. Start With Funeral Costs
Use local data or national averages ($7,000–$12,000).
2. Add Extra Family Expenses
Think about travel, time off work, or counseling.
3. Consider Inflation
If your child is young, funeral costs will likely be higher in 10–20 years.
4. Check Your Savings
Subtract any amount you could use from savings or other insurance.
For example, if you estimate $10,000 for a funeral, $3,000 for travel, and want a $2,000 cushion, you’d need $15,000 in coverage. If you have $5,000 in savings, you might only need $10,000 more in insurance.
Common Mistakes When Choosing Child Life Insurance
It’s easy to make mistakes when buying life insurance for a child. Here are a few to avoid:
- Over-insuring: Some parents buy high coverage, thinking it’s an investment. But the main purpose is protection, not savings or profit.
- Ignoring other needs: If you don’t have enough life insurance for yourself, focus there first. Your own policy protects your child more than a child policy.
- Not checking policy terms: Some child policies have restrictions or high fees to cash out early.
- Forgetting to review coverage: As your family grows or your finances change, your needs might change, too. Review your coverage every few years.
Non-obvious insight: Some people buy child life insurance mainly for the cash value, but the returns are usually much lower than other investments, like a 529 college savings plan.
Alternatives To Child Life Insurance
Before you buy, it’s smart to consider other ways to protect your family.
- Emergency fund: Saving 3–6 months of expenses can cover most emergencies, including a child’s funeral costs.
- 529 college savings plan: If your goal is to help your child financially in the future, a 529 plan grows tax-free for education.
- Parent life insurance: If you pass away, your child will need financial support. Make sure you have enough coverage for yourself first.
Here’s a simple comparison:
| Option | Main Benefit | Drawback |
|---|---|---|
| Child Life Insurance | Covers funeral, locks in future insurability | Low investment growth |
| Emergency Fund | Flexible, covers any need | Requires discipline to save |
| 529 Plan | Tax-free college savings | Only for education |
| Parent Life Insurance | Protects child if you die | Doesn’t cover child’s death |
Real-life Example
Let’s look at a real-world situation. Sarah and Mike have two kids, ages 3 and 7. They want to protect their family but have a limited budget.
- Their emergency savings: $3,000
- They estimate funeral costs: $10,000
- Extra costs (travel, time off): $3,000
Sarah and Mike decide on a $15,000 child term rider added to Mike’s life policy. It costs them $6 per month and covers both children. They choose this because they already have some savings, and their main goal is protection, not investment.
When Is More Coverage Needed?
Most families do not need more than $25,000 in child coverage. But some situations may call for more:
- Special needs: If the child has a medical condition that may make future insurance hard to get, higher coverage locks in insurability.
- No savings: Families without emergency funds may want more coverage to feel secure.
- Family preference: Some parents want a financial safety net for all possible costs.
If you’re unsure, talk to an experienced insurance agent who can answer your questions without pressuring you to buy more than you need.
How To Buy And What To Watch Out For
When you’re ready to buy, get quotes from a few companies. Read the policy details and ask about:
- Conversion options: Can the policy turn into adult coverage later?
- Premiums: Are payments fixed for life, or do they increase?
- Cash value: How does it grow, and what are the fees?
- Exclusions: Are there any situations where the policy won’t pay out?
Tip: Avoid buying from high-pressure salespeople or those who only sell one company’s products.
A good place to start research is the National Association of Insurance Commissioners.
Frequently Asked Questions
What Is The Main Reason To Buy Life Insurance For A Child?
The primary reason is to cover funeral costs and final expenses if the unthinkable happens. It can also lock in insurability, so your child can get more life insurance later, even if they develop health issues.
How Much Does Child Life Insurance Cost Per Month?
It depends on the coverage amount and type. Most child term riders cost $2–$7 per month for $10,000–$25,000 coverage. Whole life policies are more expensive, usually $5–$20 per month for similar coverage.
Is Child Life Insurance A Good Investment?
No, child life insurance is not a strong investment. The cash value grows slowly compared to other savings options. It’s better for protection than for building wealth.
Can I Add More Coverage Later?
Many policies let you increase coverage or convert to an adult policy when your child gets older. Check the specific rules with your insurance company.
Should I Buy Life Insurance For Myself Or My Child First?
It’s best to insure yourself first. Your income and support are most important for your family’s future. Child life insurance is extra protection, not a replacement.
—
Buying life insurance for your child is a personal decision. For most families, $10,000 to $25,000 in coverage is enough to provide peace of mind without overspending. Consider your own insurance, savings, and what features matter to you. Review your needs every few years. And remember, protecting your loved ones is about making smart, caring choices—not just about money.