
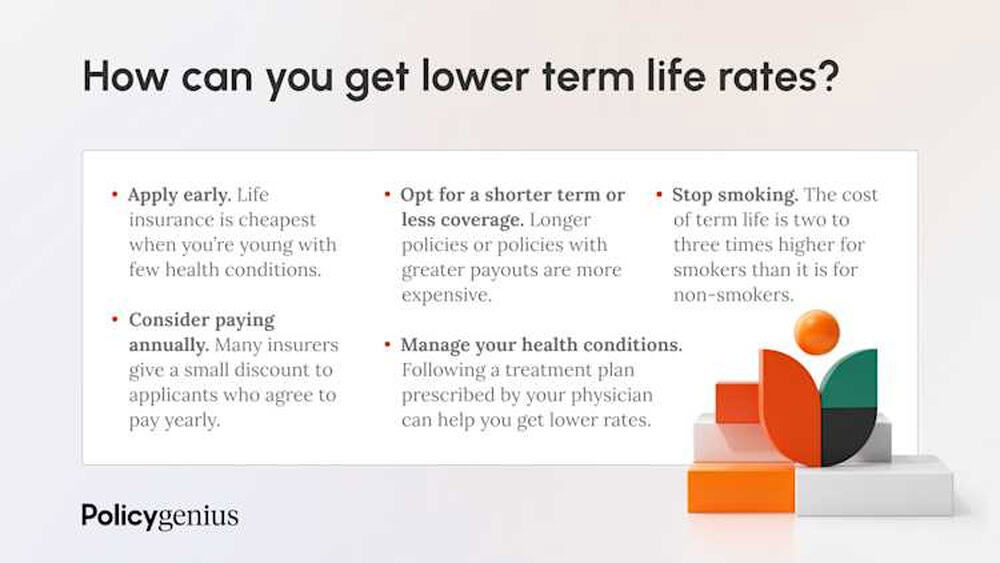
Quitting smoking is a big step toward a healthier life, and it can also save you money in unexpected ways. One area many people don’t consider is term life insurance. If you’ve stopped smoking, you might be able to get much lower rates on your policy—or even change your existing policy to reflect your new, smoke-free status. But this process isn’t always simple. Understanding how quitting smoking affects term life insurance can help you make smart decisions, protect your loved ones, and avoid common mistakes.
Why Smoking Affects Term Life Insurance
Insurance companies look at your health and lifestyle when setting your rates. Smoking is one of the biggest factors. Here’s why:

- Higher risk: Smokers are more likely to develop serious illnesses like cancer, heart disease, and lung problems.
- Shorter life expectancy: According to the CDC, smokers die about 10 years earlier than non-smokers, on average.
- More claims: Because smokers often face health issues, insurers pay out more death benefits for smokers.
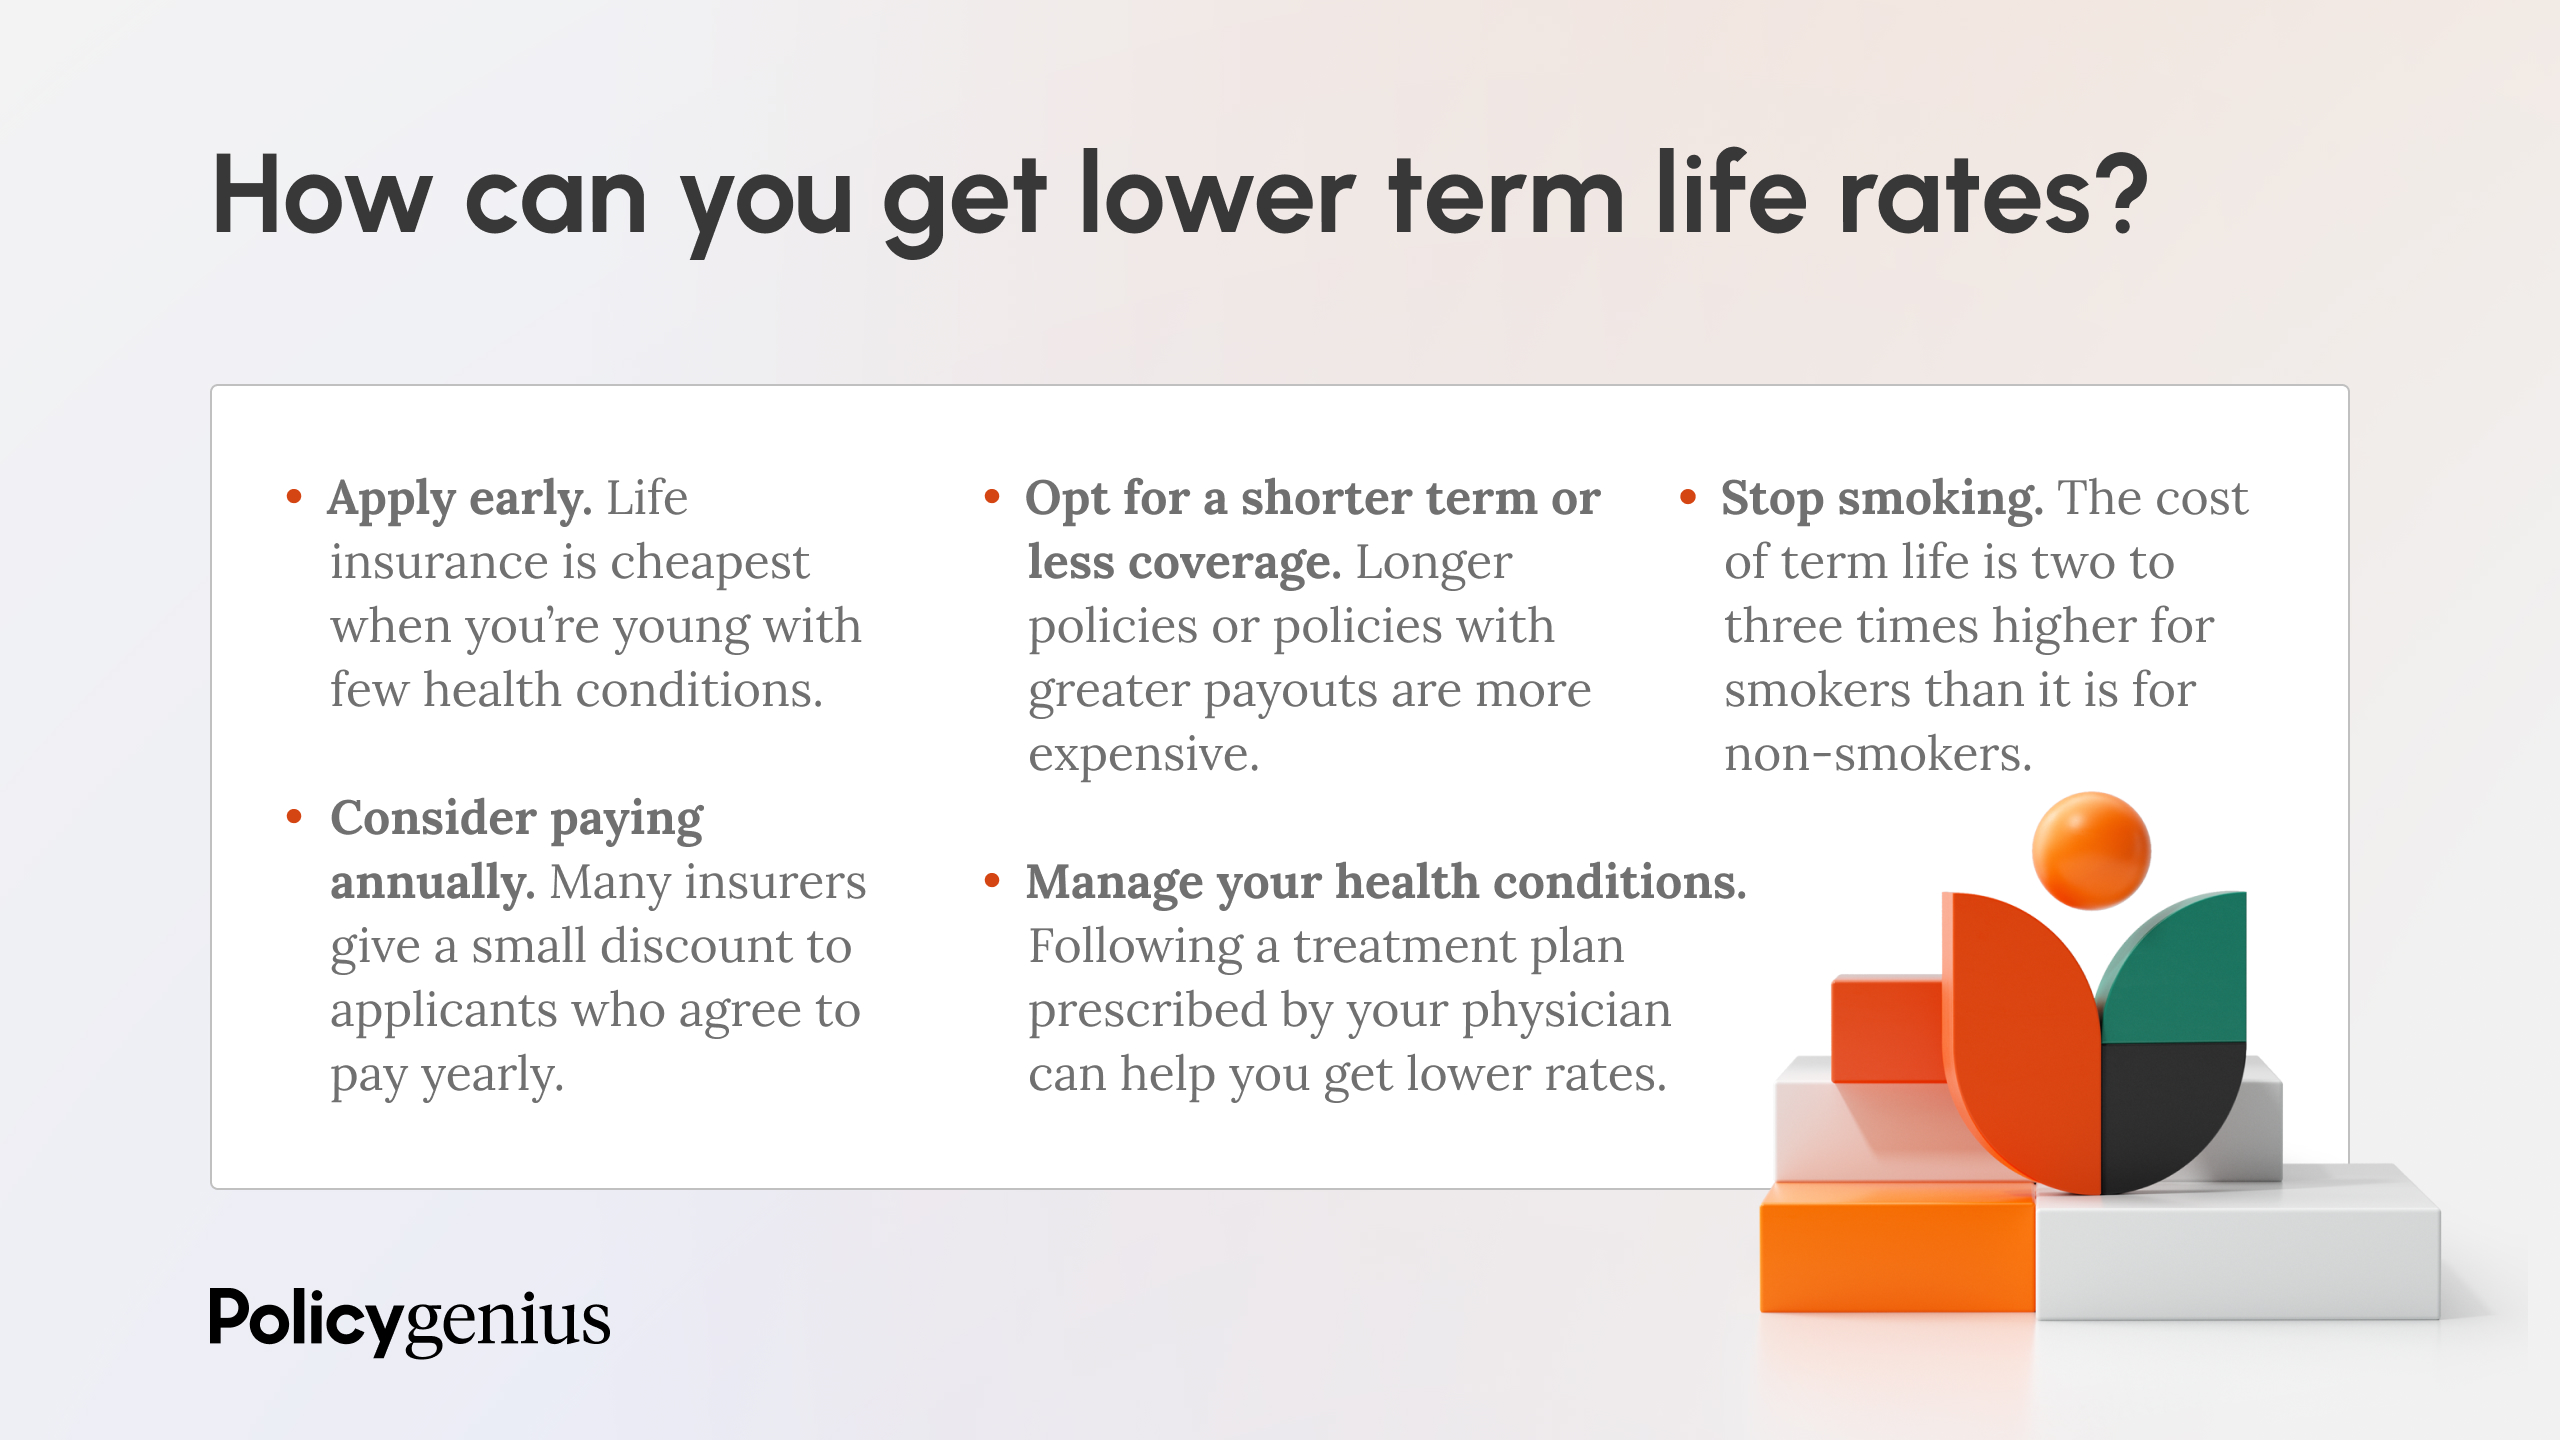
To cover these risks, companies charge smokers much higher premiums. Sometimes, smokers pay double—or even triple—the rates compared to non-smokers.
What Counts As “smoking” For Life Insurance?
You might think only cigarettes matter, but insurers look at more than that. Most companies include:
- Cigarettes
- Cigars
- Pipes
- E-cigarettes (vapes)
- Chewing tobacco
- Nicotine patches or gum
If you use any of these, you’re usually classified as a smoker. Even occasional or social smoking counts. Some companies also ask about marijuana use.
Example: How Smoking Status Affects Rates
To show the difference, here’s a sample comparison for a 35-year-old male buying a $500,000, 20-year term policy:
| Status | Monthly Premium |
|---|---|
| Non-Smoker | $27 |
| Smoker | $92 |
That’s a difference of $780 per year—and over 20 years, it adds up to $15,600 more for smokers.
How Long After Quitting Are You Considered A Non-smoker?
You can’t just quit and instantly get lower rates. Insurers want proof that you’ve stopped for a meaningful amount of time. Most companies require you to be tobacco-free for at least 12 months. Some ask for 2 years or even 5 years.
Typical Waiting Periods
| Company | Non-Smoker Status After |
|---|---|
| Company A | 12 months |
| Company B | 24 months |
| Company C | 36 months |
| Company D | 60 months |
Always check your insurer’s rules. If you try to get non-smoker rates before the waiting period, your application will likely be rejected or given smoker pricing.
How To Update Your Term Life Insurance After Quitting Smoking
If you already have a term life insurance policy as a smoker, you might want to change your status and save money. Here’s how to do it:
- Check your policy: Review your documents to see if your company allows for a rate change after quitting smoking.
- Contact your insurer: Ask how long you need to be tobacco-free and what evidence is needed.
- Prepare for medical checks: You might need to take a new medical exam or answer health questions.
- Submit proof: Provide details like doctor’s notes, lab results, or a signed affidavit.
- Wait for approval: The company will review your information and decide if you qualify for non-smoker rates.
If your insurer doesn’t allow changing your status mid-policy, you can apply for a new term life policy as a non-smoker. Compare quotes, and make sure your new policy is active before canceling your old one.
Common Mistakes When Updating Your Policy
- Not waiting long enough: Trying to update too soon can waste time and money.
- Stopping all nicotine products: Even nicotine gum or patches count as “smoking” to many insurers.
- Not being honest: If you lie on your application, your policy could be canceled or your claim denied.
- Cancelling old policy before new one starts: Always keep coverage active until your new policy is approved.
Benefits Of Quitting Smoking For Term Life Insurance
Quitting smoking has clear health benefits, but it also makes a big difference for your insurance. Here are some ways you benefit:
Lower Premiums
Smokers pay much higher premiums. After quitting, you could save hundreds or thousands of dollars per year.
Better Coverage Options
As a non-smoker, you may qualify for:
- Higher coverage amounts
- Longer terms
- More favorable health classes
Easier Approval
Quitting smoking reduces your risk profile, so you’ll have fewer medical hurdles and a smoother application process.
Real-life Example
Sarah, age 40, quit smoking three years ago. Her old policy was $500,000 coverage at $110/month as a smoker. After reapplying as a non-smoker, her rate dropped to $35/month. Over 20 years, she saves $18,000.
What Happens If You Start Smoking Again?
If you update your policy as a non-smoker but start smoking again, you must tell your insurer. If you hide it and die from a smoking-related illness, your family’s claim could be denied.
Most policies include a contestability period (usually 2 years). During this time, the insurer can check your health history and deny claims for dishonesty.
Even after the contestability period, lying about smoking is considered fraud. Always report changes in your health or habits.
How Insurers Check Your Smoking Status
Insurers don’t just take your word for it. They use several methods to check if you smoke:
- Medical exams: Blood and urine tests can detect nicotine.
- Health records: Doctors’ notes and pharmacy records.
- Application questions: Direct questions about tobacco and nicotine use.
Some companies may even check your social media for signs of smoking.
Nicotine Tests: How They Work
When you apply as a non-smoker, you may be asked to take a cotinine test (cotinine is a nicotine byproduct). It stays in your system for 7-10 days, sometimes longer.
If you use nicotine gum or patches, tell your insurer. These can trigger the test, but companies may treat them differently than cigarettes.
Comparing Term Life Insurance Rates: Smoker Vs. Non-smoker
Here’s a comparison for 30-year-old males and females buying $250,000 coverage, 20-year term:
| Profile | Male Smoker | Male Non-Smoker | Female Smoker | Female Non-Smoker |
|---|---|---|---|---|
| Monthly Premium | $60 | $18 | $45 | $15 |
| Annual Premium | $720 | $216 | $540 | $180 |
| 20-Year Cost | $14,400 | $4,320 | $10,800 | $3,600 |
The savings are huge. Quitting smoking means your premiums could drop by 60-70%.
How To Shop For Term Life Insurance After Quitting Smoking
If you’ve stopped smoking and want a new policy, follow these steps:
- Wait the required period: Make sure you meet the tobacco-free requirement (usually 12-24 months).
- Gather your health information: Be ready to show you’re in good health.
- Compare quotes: Look at several companies. Rates and waiting periods vary.
- Check for smoker reclassification: Some companies reclassify you after quitting, while others require a new application.
- Apply for the best policy: Choose the one with the best rates and coverage.
Non-obvious Insights For Shoppers
- Some companies offer “preferred non-smoker” rates if you’re in excellent health and have quit for longer (usually 2-3 years).
- If you have other health issues (like high blood pressure), quitting smoking alone may not get you the lowest rates. Work on overall health for best results.
Special Cases: Occasional Smokers And Vapers
Not everyone fits neatly into “smoker” or “non-smoker.” If you vape or smoke occasionally, here’s what to expect:
- Vaping: Most insurers treat it as smoking, but some may offer special rates.
- Cigars: If you smoke cigars rarely (like once a year), some companies may classify you as a non-smoker.
- Marijuana: Rules vary. If you only use marijuana, ask your insurer how it affects rates.
Always be honest and ask questions. Some policies have exceptions, but most treat any nicotine use as smoking.
Practical Tip
If you’re switching from cigarettes to vaping or nicotine patches, keep in mind these still count as “smoking” for insurance. Wait until you are completely nicotine-free for the required period.
Common Questions And Misconceptions
Many people misunderstand how term life insurance handles quitting smoking. Let’s clear up a few:
- “I only smoked once, am I a smoker?” If you’ve used tobacco in the past year, most companies count you as a smoker.
- “Can I get non-smoker rates if I use nicotine gum?” Usually not. Gum and patches are seen as “tobacco use.”
- “Will quitting smoking lower my existing policy rate?” Maybe. Some companies allow rate changes, but many require a new policy.
Tips For Getting The Best Term Life Insurance Rates After Quitting Smoking
- Improve overall health: Losing weight, exercising, and controlling blood pressure can help you qualify for better rates.
- Keep medical records: Having documentation from your doctor about quitting smoking is helpful.
- Shop around: Some companies are stricter than others. Compare at least 3-5 insurers.
- Be honest: Always tell the truth on your application. Dishonesty can lead to denial.
- Consider timing: Apply after the waiting period, but don’t wait too long—rates go up as you age.
Extra Insight
Some insurers offer “smoker to non-smoker conversion” policies. These allow you to switch to lower rates after quitting, without a new application. Ask about this option when shopping.
Impact On Your Family And Future
Quitting smoking not only saves money but also means your family is more likely to get a payout if something happens to you. Life insurers can deny claims if you lied about smoking. Being honest protects your loved ones and your investment.
Your improved health also means you’re more likely to live longer and support your family. Term life insurance is about peace of mind—and quitting smoking is a key part of that.
Frequently Asked Questions
What Happens If I Quit Smoking After Buying Term Life Insurance?
You can ask your insurer to reclassify you as a non-smoker after the required tobacco-free period (usually 12-24 months). Some companies allow this, but others may require you to buy a new policy. Always check your policy’s rules.
How Do Insurers Verify My Smoking Status?
Insurers use medical exams, blood or urine tests, health records, and application questions. Sometimes, they check your doctor’s notes or pharmacy history. Cotinine tests are commonly used to detect nicotine in your system.
Can I Get Lower Rates If I Use Nicotine Gum Or Patches?
Most insurers count any nicotine use—including gum and patches—as “smoking. ” To qualify for non-smoker rates, you must be completely nicotine-free for the required period.
Will My Rates Go Up If I Start Smoking Again?
Yes. If you become a smoker after being classified as a non-smoker, you must tell your insurer. Your rates could go up, and lying could result in denied claims or canceled policies.
Is Vaping Considered Smoking For Life Insurance?
Usually, yes. Most insurers treat vaping as smoking, but some may have special rules. Always check with your insurer before applying.
Quitting smoking is a powerful step for your health and your finances. Understanding how it affects term life insurance can help you protect your family, save money, and enjoy the benefits of a smoke-free life. If you have questions or want to learn more, visit the CDC Tobacco Data for trusted information. Remember, every year you stay smoke-free is a gift—to yourself and your loved ones.