
Yes, you can get life insurance with sleep apnea. Most major US insurers approve applicants who use CPAP or another treatment, and many offer standard rates once your condition is managed and stable.
How life insurance views sleep apnea
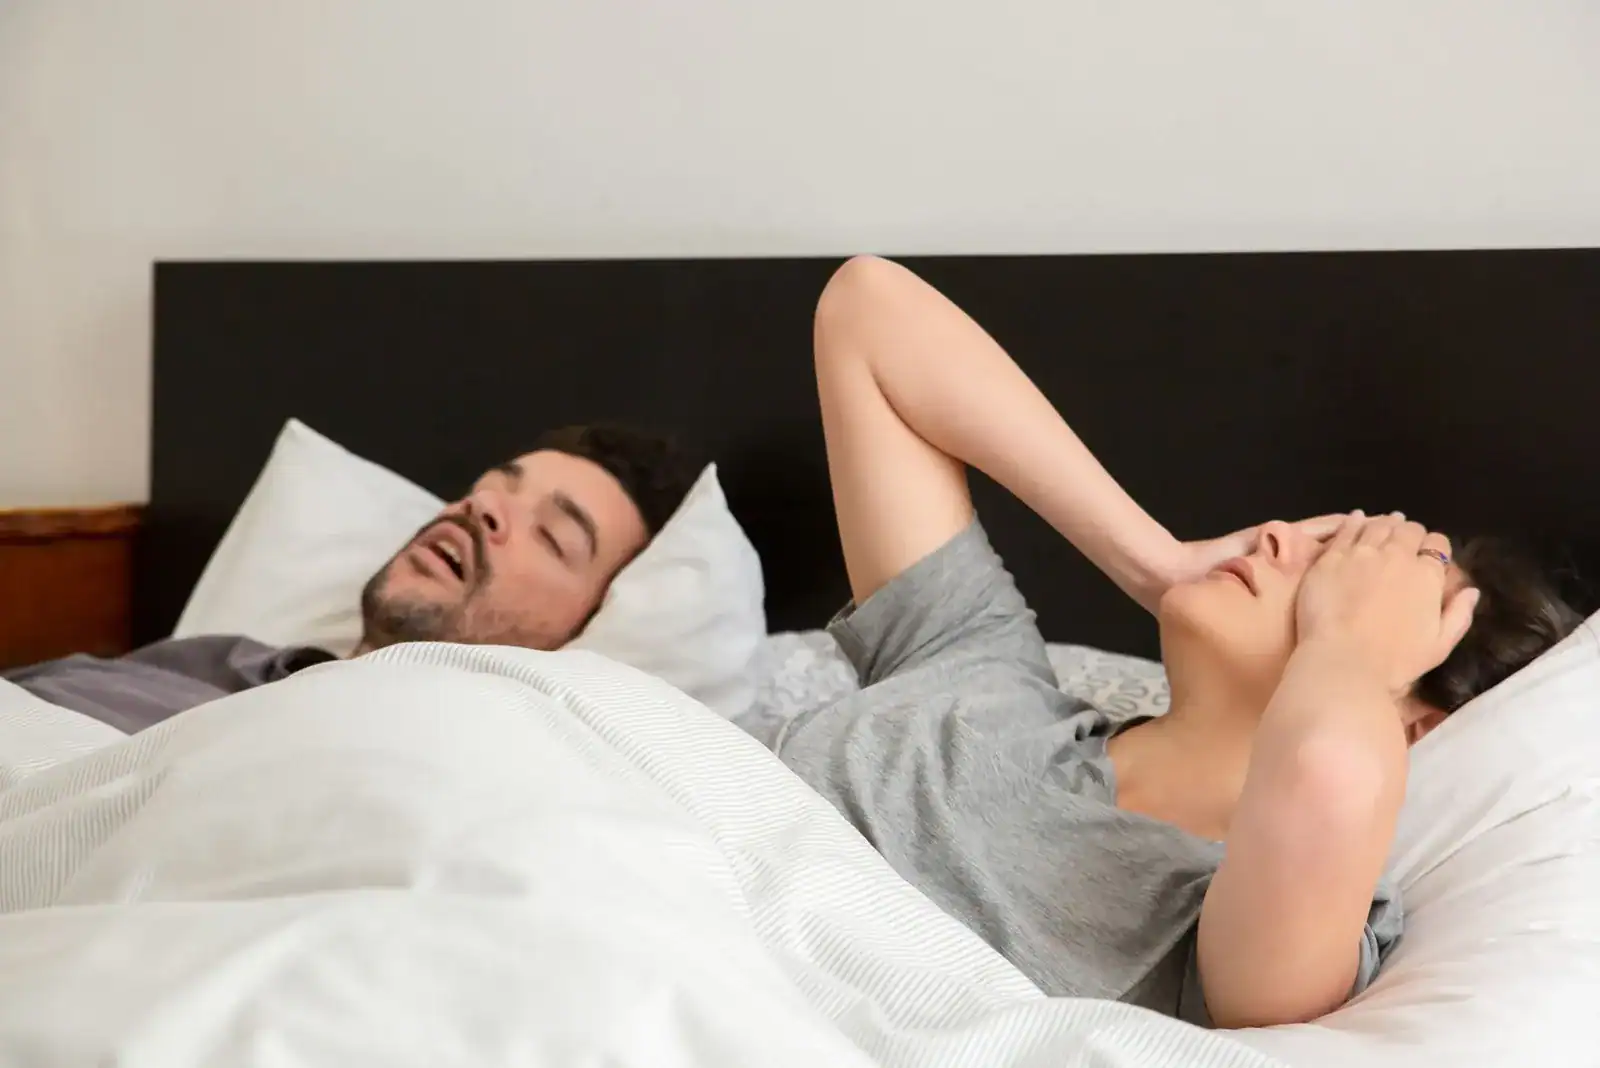
Insurance companies don’t reject you just because you have sleep apnea. They look at a few specific things:

- Your diagnosis. A formal sleep study result matters more than symptoms alone.
- Your AHI number. This is the apnea-hypopnea index from your sleep study. Under 5 is normal, 5-15 is mild, 15-30 is moderate, and over 30 is severe.
- Your treatment. CPAP use, an oral appliance, or surgery all count. Insurers want proof you’re treating it.
- Your overall health. Blood pressure, weight, and heart conditions linked to untreated apnea affect your rate.
If your AHI is below 20 and you use CPAP consistently, you’ll usually qualify for standard rates. Severe, untreated apnea is where approval gets harder.
How Your AHI Affects Your Rate
The table below shows how insurers typically classify sleep apnea severity. Your exact rate depends on the insurer and your other health factors.
| AHI Range | Severity | Typical Rating |
|---|---|---|
| Under 5 | Normal | Preferred rates possible |
| 5-15 | Mild | Standard rates |
| 15-30 | Moderate | Standard to table-rated |
| Over 30 | Severe | Table-rated or declined if untreated |
A “table rating” means you pay more than standard because the insurer sees higher risk. Treated severe apnea can still get approved, but usually at a higher premium.
Steps to Improve Your Approval Chances
There’s no single form to fill out, but the order below helps most people.
- Get a sleep study on record. A confirmed diagnosis with your AHI number gives insurers something concrete to review.
- Use your CPAP consistently. Insurers may request a compliance report showing you use it most nights.
- Lower your AHI if you can. Weight loss, positional therapy, or surgery can reduce severity before you apply.
- Control related conditions. Keep blood pressure and heart health in check, since these often decide your final rate.
- Apply when your numbers are stable. A recent, well-managed reading beats an old, untreated one.
- Work with an agent who knows impaired-risk cases. They can match you to insurers that handle apnea well.
Tip: Ask your sleep clinic for a compliance download before you apply. A clear CPAP usage report can move you from a higher rating to a standard one.
When It’s Harder to Get Covered
Some situations make approval tougher or push your premium higher.
- Untreated severe apnea. An AHI over 30 with no CPAP use is the hardest case to place.
- Recent diagnosis. Insurers often want to see a few months of stable treatment first.
- Other health problems. Diabetes, heart disease, or stroke linked to apnea raise your risk class.
- Certain medications or surgeries. These get reviewed case by case.
The gap between a decline and an approval is often just proof. A machine report showing nightly use, or a letter from your sleep doctor noting your AHI has dropped on treatment, moves a file from the decline pile to a standard rate.
If you’re declined by one insurer, that doesn’t mean all of them will say no. Different companies have different rules for sleep apnea.
Ask what the decline was based on. If it was the untreated reading, get treated and reapply in six to twelve months. If it was a second condition, you need a carrier that prices that condition rather than one that avoids it.
Frequently Asked Questions
Can I get life insurance if I don’t use CPAP?
Yes, but it’s harder. Insurers want to see that your apnea is treated, so untreated cases often get higher rates or a decline. If you can’t tolerate CPAP, an oral appliance or surgery may work instead.
Do I need a sleep study to qualify?
Most insurers ask for one. A sleep study gives your AHI number, which is the main figure they use. Without it, they may postpone your application until you have a diagnosis.
Will sleep apnea make my premium much higher?
Not always. Mild or moderate apnea with consistent CPAP use often gets standard rates. Severe, untreated cases cost more or get declined. Your rate depends on your AHI, treatment, and overall health.
Conclusion
Get your sleep study results and a CPAP compliance report in hand before you shop for coverage. Those two documents do more for your approval than anything else. If you’ve been declined before, talk to an agent who works with sleep apnea cases — a different insurer may see your situation very differently.