
Many people wonder if life insurance or health insurance is the better choice for their needs. This question comes up often, especially for beginners who are just starting to think about their financial security. Both types of insurance offer important protection, but they do different things. It can be confusing to decide which one to buy, especially if you do not understand how they work. In this article, you will learn what life insurance and health insurance are, how they compare, and which one may fit your situation best. You will also see real examples, simple explanations, and practical advice to help you make the right decision.
What Is Life Insurance?
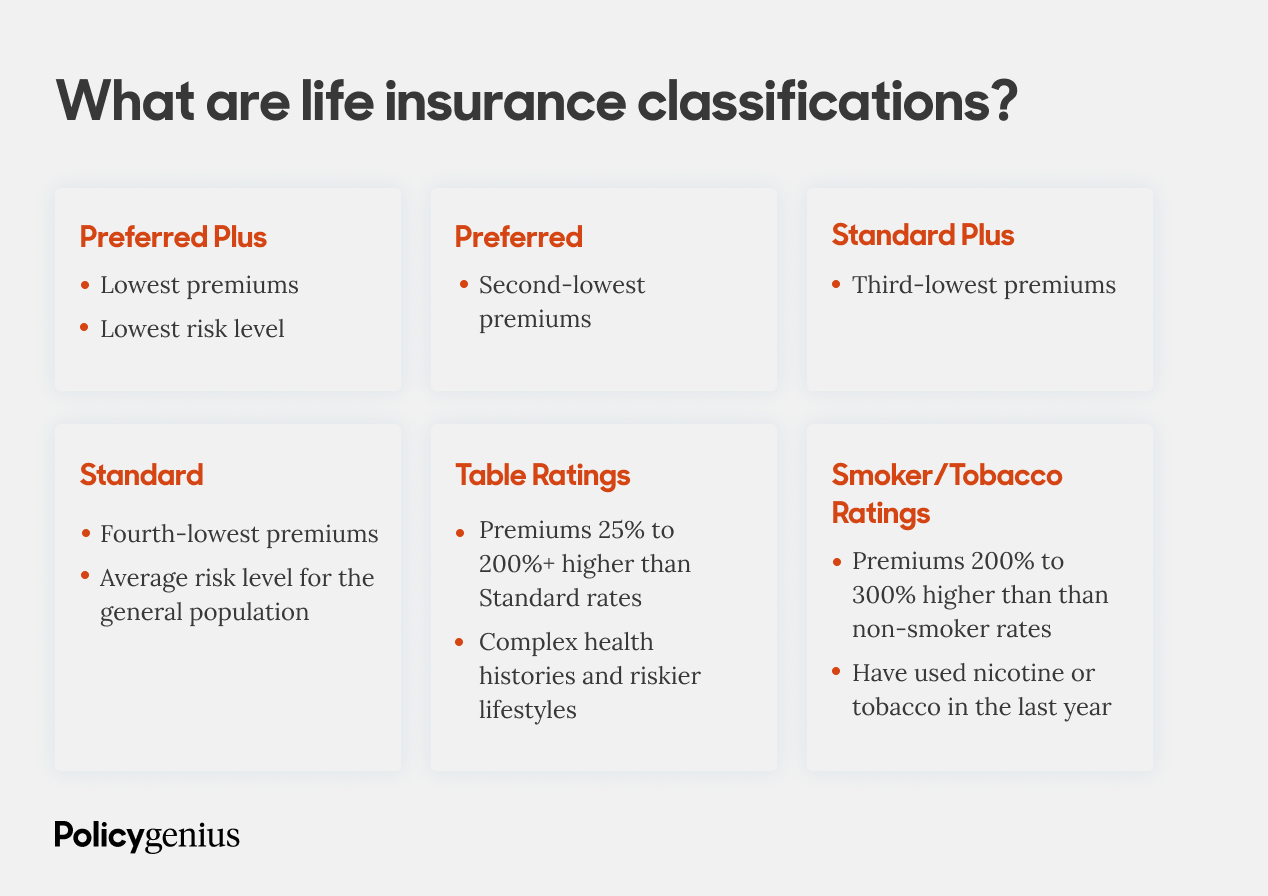
Life insurance is a contract between you and an insurance company. You pay a regular fee, called a premium. If you die while the policy is active, your family or loved ones get a lump sum of money. This money is called a death benefit. The main purpose of life insurance is to help your family manage financially after you are gone. It can be used to pay off debts, cover living expenses, or pay for children’s education.

There are two main types of life insurance:
- Term life insurance: Covers you for a set period, like 10, 20, or 30 years. If you die during that time, your family gets the benefit. If you live past the term, the policy ends and you get nothing.
- Whole life insurance: Covers you for your entire life. It is more expensive, but sometimes has a savings feature called cash value.
Most beginners choose term life insurance because it is simple and cheaper. According to the National Association of Insurance Commissioners (NAIC), the average annual premium for a healthy 30-year-old buying a $250,000, 20-year term policy is about $200–$300.
What Is Health Insurance?
Health insurance is a contract that helps pay for your medical bills. You pay a premium, and the insurance company pays part of the cost when you go to the doctor, hospital, or need medicine. The main goal of health insurance is to protect you from high medical expenses. Without insurance, even a short hospital stay can cost thousands of dollars.
Health insurance usually covers:
- Doctor visits
- Hospital stays
- Surgery
- Medicine
- Emergency care
There are many plans, but the most common in the US are HMO (Health Maintenance Organization) and PPO (Preferred Provider Organization). Health insurance can also cover preventive care like vaccines and check-ups.
The Kaiser Family Foundation reports that the average annual premium for single coverage in the US is about $7,739 (for employer-sponsored plans), with employers paying most of this amount.
Key Differences: Life Insurance Vs Health Insurance
To make things clearer, let’s look at a simple comparison of the main features:
| Feature | Life Insurance | Health Insurance |
|---|---|---|
| Purpose | Supports family after death | Pays for medical care |
| Benefit | One-time payout (death benefit) | Ongoing payments for medical bills |
| Who gets the money? | Family or chosen person | You or your doctor/hospital |
| When is it used? | After policyholder dies | When you need medical treatment |
| Typical cost | $200–$300/year (term, young adult) | $7,739/year (single, average) |
Many beginners miss that life insurance does not help with your own health costs. It is for your family if you die. Health insurance helps you while you are alive and facing health issues.
Who Needs Life Insurance?
Life insurance is best for people who have dependents. That means someone relies on your income, like children, a spouse, or elderly parents. If you are the main earner and something happens to you, your family could face money problems.
Reasons you might need life insurance:
- You have children who need support
- You have a spouse who depends on your income
- You have debts like a mortgage or student loans
- You want to leave money for funeral costs
If you are single, have no dependents, and no big debts, you may not need life insurance right now. But if your situation changes, you should review your options.
Who Needs Health Insurance?
Almost everyone needs health insurance, no matter their age or family status. Medical costs can happen anytime, and they can be very high. Even healthy people can get sick or have accidents. Health insurance helps you:
- Pay for routine check-ups
- Cover emergency medical bills
- Manage chronic illnesses
- Avoid large debt from hospital costs
In many countries, health insurance is required by law. In the US, some states still have penalties for not having coverage. It is risky to go without health insurance because one unexpected event can cost more than most people can pay.
Pros And Cons Of Life Insurance
Understanding the benefits and drawbacks can help you decide if life insurance is right for you.
Pros
- Protects your family: Gives financial support after your death.
- Covers debts: Helps pay off loans, mortgage, or credit cards.
- Affordable for young people: Term policies are cheap for healthy, young adults.
- Peace of mind: You know your loved ones will be safe.
Cons
- Does not help with health costs: No coverage for medical bills.
- Not needed for everyone: If you have no dependents, it may not be useful.
- Some types are expensive: Whole life insurance costs much more.
Many beginners miss that buying more insurance than needed can waste money. Only buy what fits your family’s needs.
Pros And Cons Of Health Insurance
Now let’s look at the advantages and disadvantages of health insurance.
Pros
- Pays for medical expenses: Helps with doctor, hospital, and medicine bills.
- Protects savings: Prevents large medical debt.
- Access to better care: You can get treatment without worrying about cost.
- Covers preventive care: Vaccines and check-ups are often included.
Cons
- Can be expensive: Premiums and deductibles may be high.
- Not all treatments covered: Some plans have limits.
- Complex choices: Many plans and rules can be confusing.
A common mistake is ignoring hidden costs like deductibles (what you pay before insurance helps) and co-pays (small fees for each visit).
How To Choose: Life Insurance Or Health Insurance?
Choosing between life insurance and health insurance depends on your situation. Here are some steps to help you decide:
- Check your dependents: If someone relies on your income, life insurance is important.
- Look at your health risks: Everyone faces health risks, so health insurance is almost always needed.
- Review your budget: Can you afford both types? Many people start with health insurance, then add life insurance when their family grows.
- Think about your goals: Are you worried about your family’s future or your own medical costs?
- Understand your country’s laws: Some places require health insurance.
Here is a comparison of common situations:
| Situation | Best Choice | Why? |
|---|---|---|
| Single, young, healthy | Health Insurance | Protects against medical costs; no dependents |
| Married, children | Both | Family needs support and you need medical coverage |
| Older, with health issues | Health Insurance | Medical needs are high; life insurance may be costly |
| Young family, mortgage | Both | Protects home, family, and health |
| No family, high debts | Health Insurance | Protects against medical bills; debts may be managed |
Many beginners overlook that you can have both types of insurance. They are not mutually exclusive. If you can afford it, having both brings better overall security.
Common Mistakes Beginners Make
When buying insurance for the first time, people often make mistakes:
- Buying too much insurance: Only buy what you need. Extra coverage can waste money.
- Ignoring hidden costs: Look for deductibles, co-pays, and exclusions.
- Not updating coverage: Life changes—marriage, children, job loss—should lead to reviewing your insurance.
- Choosing price over coverage: Cheapest is not always best. Make sure the plan covers what matters.
- Forgetting about waiting periods: Some health insurance plans have waiting times for certain treatments.
A non-obvious tip: Always read the policy details. Insurance contracts can have small print that changes what you get.
Real-life Examples
Let’s look at two simple examples that show how these insurances work.
Example 1: Maria, age 28, is single and healthy. She buys health insurance to cover doctor visits and emergencies. She does not need life insurance now.
Example 2: John, age 35, is married with two kids. He buys term life insurance for $500,000 to protect his family if he dies. He also gets health insurance for daily medical needs.
In both cases, the right insurance fits their life stage and needs.
How Much Coverage Do You Need?
It’s important not to guess how much insurance to buy.
- For life insurance: A common rule is to buy coverage worth 10–15 times your yearly income. For example, if you earn $40,000, you may want $400,000–$600,000 of coverage.
- For health insurance: Look for a plan that covers major medical costs, routine care, and prescriptions. Check the out-of-pocket maximum—the most you pay in a year.
Comparing Costs And Benefits
Here’s another simple data table showing average costs and benefits:
| Type | Average Cost | Main Benefit |
|---|---|---|
| Term Life Insurance | $200–$300/year (young adult) | Family gets lump sum if you die |
| Whole Life Insurance | $1,000–$2,000/year (young adult) | Lifetime coverage, cash value |
| Health Insurance (Single, US) | $7,739/year (average) | Pays for medical bills, routine care |
You can see that health insurance is usually more expensive, but it is used more often.
Expert Guidance
If you are still unsure, it can help to talk to a professional. Insurance agents can explain options, but always check if they are trustworthy and not just selling. You can also read more about insurance on the official government websites. One helpful resource is the Healthcare.gov site, which offers clear information for beginners.
Final Thoughts
Both life insurance and health insurance are important, but they serve different purposes. Life insurance protects your loved ones after you die, while health insurance protects you from medical costs while you are alive. Beginners often think they must choose only one, but you can have both if your budget allows.
Start with health insurance if you need to cover daily medical costs, and add life insurance if you have a family or dependents. Take your time, compare options, and don’t be afraid to ask questions. The right choice depends on your life stage, financial goals, and who depends on you.
Frequently Asked Questions
What Is The Main Difference Between Life Insurance And Health Insurance?
Life insurance pays your family if you die. Health insurance pays for your medical bills while you are alive.
Can I Have Both Life Insurance And Health Insurance?
Yes, you can buy both if you want. Many people do, especially if they have a family and want full protection.
Is Health Insurance Required By Law?
In some countries and US states, health insurance is required. Always check the rules where you live.
How Much Life Insurance Should I Buy?
A common rule is to get coverage worth 10–15 times your yearly income. This helps your family manage after you are gone.
What Happens If I Skip Health Insurance?
You may have to pay the full cost of medical care, which can be very expensive. Some places may also charge a penalty for not having insurance.