Choosing the best life insurance policy for your family can feel confusing. There are many terms, numbers, and options to compare. But life insurance is one of the most important steps you can take to protect your loved ones. The right policy gives financial security if something happens to you.
With some clear steps and smart tips, you can find a policy that fits your family’s needs and budget.

Understand Why Your Family Needs Life Insurance
Many people buy life insurance to replace lost income after death. It helps pay for living expenses, debts, or education for children. But every family is different. Some need only a small safety net, while others want to cover a mortgage or large debts.
Ask yourself:
- Does your family depend on your income?
- Do you have loans or a mortgage?
- Will your children need college funds?
- Are there other people who rely on you financially?
These questions help you decide how much coverage is right.
Know The Main Types Of Life Insurance
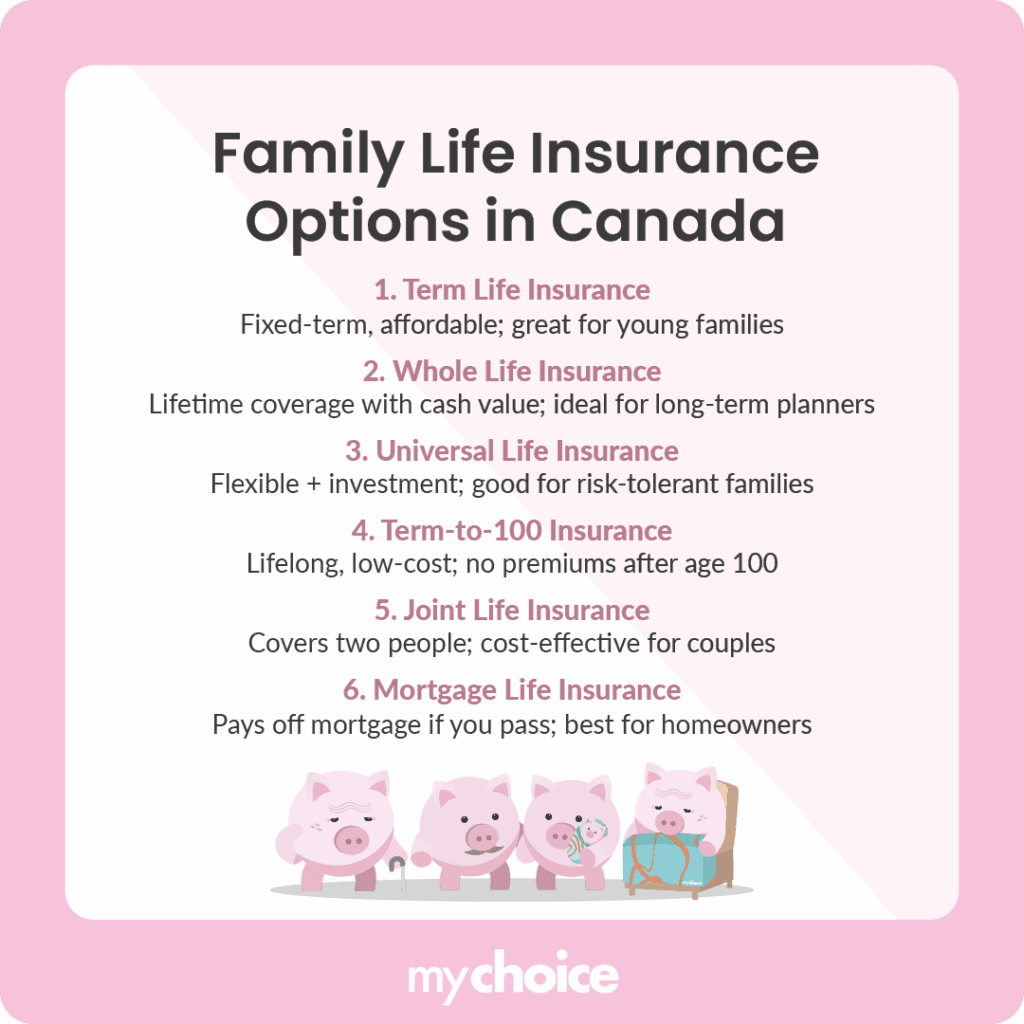
There are two main types: term life and permanent life insurance. Each works differently. Use the table below to compare them:
| Type | How It Works | Cost | Best For |
|---|---|---|---|
| Term Life | Covers you for a fixed period (e.g., 10, 20, 30 years). Pays if you die during the term. | Lower premiums | Most families, parents with young kids |
| Whole Life | Covers you your whole life. Builds cash value. | Higher premiums | People who want lifelong coverage and savings |
| Universal Life | Flexible premiums and coverage. Builds cash value. | Varies | Those seeking flexibility and investment |
Most families choose term life because it’s affordable and simple. But permanent policies offer benefits like cash value, which you can borrow against.
Decide How Much Coverage You Need
A common rule is to buy life insurance worth 10 to 15 times your yearly income. But every family’s needs are unique. Consider the following costs:
- Daily living expenses (food, bills, childcare)
- Mortgages or rent
- Outstanding loans (car, student, credit card)
- Future education costs
- Funeral expenses
Here’s a simple example:
If you earn $40,000 a year, and want 10x coverage, you’d look for a $400,000 policy.
But don’t just guess. Many insurance companies have online calculators to help. Also, don’t forget inflation—college and living costs rise over time.
Compare Policies And Providers
Not all policies are equal. The company’s financial strength and customer service matter. Use ratings from agencies like A.M. Best, Moody’s, or Standard & Poor’s to check a company’s reliability.
Look for:
- Stable companies with good ratings (A or higher)
- Easy claim process
- No hidden fees or confusing terms
- Positive reviews from real customers
Comparing policy features is also important. This table shows what to watch for:
| Feature | Why It Matters | Questions to Ask |
|---|---|---|
| Convertibility | Lets you switch from term to permanent insurance later | Is this option included? |
| Riders | Add extra coverage (disability, child, accident) | Are riders affordable and useful? |
| Renewal Options | Allows you to renew after the term ends | How much will renewal cost? |
Watch Out For Common Mistakes
Many people make simple mistakes when buying life insurance. Here’s what to avoid:
- Underestimating your needs: People often buy too little coverage. Think about long-term costs, not just today.
- Choosing the cheapest policy only: Low cost can mean less coverage or hard-to-understand terms. Balance price with quality.
- Not reviewing policies regularly: Life changes—marriage, kids, new jobs. Update your coverage as your needs change.
- Ignoring health questions: Hiding health issues can void your policy. Always answer honestly.
- Forgetting about inflation: What seems like enough today may not be enough in ten years.
A less obvious tip: Check if your employer’s insurance is enough. Many work policies cover only 1–2 times your salary, which is rarely enough for families.
The Application Process: What To Expect
Applying for life insurance is straightforward but can take time. Here’s what usually happens:
- Get quotes: Compare prices and features online or with an agent.
- Fill out an application: Share your health history, lifestyle, and job details.
- Medical exam: Most companies require a simple health check. Some “no exam” policies exist, but they cost more.
- Wait for approval: It can take days or weeks. The company reviews your information.
- Sign and pay: Once approved, review the policy, sign, and make your first payment.
Tip: Prepare your medical and financial details before you apply. This speeds up the process.

When To Review Or Change Your Policy
Life is always changing. Check your policy every few years or after major events:
- Marriage or divorce
- Birth or adoption of a child
- Buying a home
- Starting a business
- Large salary changes
Reviewing helps make sure your family is always protected. Don’t be afraid to switch companies if you find a better deal.
Frequently Asked Questions
How Much Life Insurance Does A Family Really Need?
Most experts suggest 10–15 times your annual income. But factor in debts, children’s education, and daily expenses. Use calculators or speak with a trusted advisor for a more exact number.
What Is The Difference Between Term And Whole Life Insurance?
Term life covers you for a set period and is usually cheaper. Whole life covers you for life, costs more, but builds cash value that you can use. Decide based on your budget and if you want a savings feature.
Can I Have More Than One Life Insurance Policy?
Yes, you can own several policies from different companies. Many people combine work insurance with personal policies for better coverage.
What Happens If I Miss A Payment?
Most policies give a grace period (usually 30 days). If you pay during this time, your policy stays active. Miss the grace period, and your coverage may end. Always ask your provider for details.
Where Can I Compare Life Insurance Policies?
Many websites let you compare quotes and features. For reliable information, try NerdWallet, a trusted resource.
Choosing the best life insurance policy is not a one-time task. Your family’s needs can change, so review your coverage every few years. Take your time, ask questions, and make sure you understand your policy before signing. The right life insurance gives peace of mind—knowing your loved ones will be protected, no matter what happens.