
If you receive Supplemental Security Income (SSI), finding the right life insurance is not always simple. SSI recipients must follow strict income and asset rules, so a life insurance policy could affect their benefits. At the same time, protecting your loved ones and covering final expenses is important. The good news: There are life insurance options that can work for SSI recipients, but you must be careful and informed. This article explains everything you need to know, including what to look for, which types of policies to consider, and how to avoid common mistakes.
Why Life Insurance Matters For Ssi Recipients
Many SSI recipients worry about leaving financial burdens behind. Funerals, unpaid bills, or even debts can fall on loved ones. Life insurance can cover these costs, but the wrong policy may put your SSI benefits at risk. SSI is a need-based program. If your assets go over the limit, you could lose your monthly payments and Medicaid. So, choosing the right kind of life insurance is about protecting both your family and your benefits.

Understanding Ssi Rules And Life Insurance
Before buying any policy, it’s critical to understand how the Social Security Administration (SSA) treats life insurance. SSI recipients can only have a small amount of “countable resources.” If your life insurance has a cash value or savings component, it could count as a resource.
- Resource limits: SSI recipients can own up to $2,000 in countable resources ($3,000 for couples).
- Exempt life insurance: The cash value in a whole life or burial policy is exempt up to $1,500 per person if it’s meant for funeral expenses.
- Term life insurance: This type has no cash value, so it doesn’t count as a resource.
If you go over the resource limit, even by a small amount, your SSI could stop.
Types Of Life Insurance For Ssi Recipients
Each type of life insurance has pros and cons for SSI recipients. Here’s a closer look at your main options.
Term Life Insurance
Term life insurance covers you for a set period, such as 10, 20, or 30 years. If you die during the term, your family receives a payout. If you outlive the policy, coverage ends.
- Pros: No cash value, so it won’t count against SSI resources. Usually cheaper than whole life. Simple to understand.
- Cons: Coverage ends after the term. Not guaranteed for life. If your health changes, renewing may be difficult.
Final Expense (burial) Insurance
Final expense insurance is a small whole life policy meant to cover funeral and burial costs. Coverage is usually between $2,000 and $25,000.
- Pros: Easy to qualify, even with health problems. Can be structured so the cash value stays under SSI limits.
- Cons: Higher premiums per dollar of coverage. Cash value counts toward SSI resource limits if over $1,500.
Whole Life Insurance
Whole life insurance offers coverage for your entire life and builds cash value over time.
- Pros: Guaranteed payout if you keep up payments. Builds cash value.
- Cons: Cash value over $1,500 counts against SSI. Premiums are higher. May put your benefits at risk if not managed carefully.
Group Life Insurance
Some people get group life insurance through an employer or membership organization.
- Pros: May not require medical exams. Sometimes free or low-cost.
- Cons: Usually ends when you leave the job or group. May not be enough coverage. Check if there’s any cash value.
Comparing Life Insurance Options For Ssi Recipients
Not all policies are equal. Here’s a side-by-side look at the most common choices:
| Type of Policy | Cash Value | SSI Resource Impact | Typical Coverage | Easy to Qualify? |
|---|---|---|---|---|
| Term Life | No | No impact | $25,000–$1,000,000+ | Depends on health |
| Final Expense | Yes (small) | Exempt up to $1,500 | $2,000–$25,000 | Yes |
| Whole Life | Yes | Counts if over $1,500 | $5,000–$1,000,000+ | Depends on health |
| Group Life | Rarely | Usually no impact | $5,000–$50,000 | Yes |
Key Features To Look For In Life Insurance For Ssi Recipients
Finding the right policy is more than just picking the lowest price. Here’s what matters most:
- No cash value (or low cash value): Term policies are safest. If you choose whole or burial insurance, make sure the cash value never goes over $1,500.
- Coverage amount: Only buy what you need. Too much coverage may increase your cash value and risk your SSI.
- Simple application: Many SSI recipients have health issues. Look for policies with easy underwriting or guaranteed acceptance.
- Affordable premiums: Make sure you can keep up with payments. Lapsed policies may waste your money.
- Trusted insurer: Choose a financially strong company with good reviews and a clear claims process.
The Best Life Insurance Companies For Ssi Recipients
Based on these rules, some companies stand out for SSI-friendly options. Here’s a look at providers that often work well for people on SSI. Remember, your choices may be different depending on your health, age, and location.
1. Mutual Of Omaha
Mutual of Omaha is well-known for final expense insurance. Their policies are easy to qualify for and they understand SSI rules.
- Coverage: $2,000–$25,000
- Cash Value: Yes, but stays small if you choose a low amount
- Age Range: 45–85
- Medical Exam: Not required
2. Aig
AIG offers guaranteed issue whole life, which means you can’t be turned down for health reasons. Their policies are popular for seniors on SSI.
- Coverage: $5,000–$25,000
- Cash Value: Yes, monitor carefully to stay under SSI limits
- Age Range: 50–80
- Medical Exam: Not required
3. State Farm
State Farm has term and final expense options. Their agents often know how to help SSI recipients choose safe products.
- Coverage: $10,000–$250,000+
- Cash Value: Only on some policies
- Age Range: Varies
- Medical Exam: Sometimes required
4. Colonial Penn
Colonial Penn specializes in guaranteed acceptance life insurance. This can work for people with health problems.
- Coverage: $2,000–$50,000
- Cash Value: Yes, but limited
- Age Range: 50–85
- Medical Exam: Not required
5. Globe Life
Globe Life offers simple, low-cost policies with no medical exams. Good for people who want basic coverage.
- Coverage: $5,000–$100,000
- Cash Value: Only on some products
- Age Range: Varies
- Medical Exam: Not required
6. Gerber Life
Gerber Life is known for policies that cover children and adults, including guaranteed acceptance plans.
- Coverage: $5,000–$25,000
- Cash Value: Yes, but limited
- Age Range: 50–80 (for guaranteed acceptance)
- Medical Exam: Not required

How Life Insurance Affects Ssi Benefits
This is where many people make mistakes. Here’s what you need to know:
- Cash value over $1,500: If your policy’s cash value grows over $1,500, the extra amount counts toward your SSI resource limit.
- Term insurance: No cash value, so it’s always safe.
- Prepaid burial plans: If you buy an irrevocable burial contract (cannot be changed or cashed out), it does not count as a resource.
Example
Maria has a $10,000 burial insurance policy with a current cash value of $900. This is exempt because it’s under $1,500. If the cash value grows to $1,600, $100 will count as a resource. If Maria’s other countable assets are $1,950, she will go over the $2,000 limit and lose SSI.
Steps To Buy Life Insurance Without Risking Ssi
- Check your current resources. Make sure you know your bank balance, assets, and existing policies.
- Choose term life or a small final expense policy. Avoid large whole life policies.
- Ask the insurer about cash value. Before you buy, confirm how fast it grows.
- Keep proof of purpose. If the policy is meant for burial, keep documents in case SSI asks.
- Review each year. Cash value may grow slowly, but check so you don’t go over the limit.
- Work with an agent who knows SSI. Not all agents understand these rules.

Common Mistakes Ssi Recipients Make With Life Insurance
It’s easy to make errors that threaten your benefits. Here are some to avoid:
- Ignoring cash value: Many people buy whole life insurance and forget that the cash value will one day count against their SSI.
- Buying too much coverage: The bigger the policy, the higher the risk that the cash value will exceed $1,500.
- Not reviewing policies: Cash value grows over time. Even if you’re safe now, you might go over the limit in 5-10 years.
- Assuming all burial policies are exempt: Only the first $1,500 in cash value is exempt for burial purposes.
- Letting a family member pay for life insurance: If someone else pays the premiums, it could be considered a gift and affect your SSI.
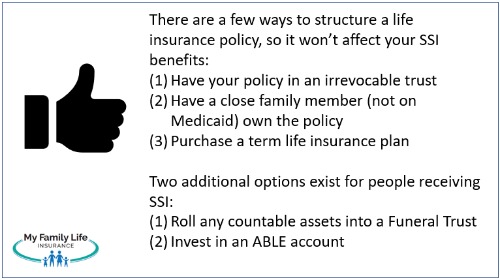
How To Structure Your Life Insurance To Protect Ssi
You have options for making your policy SSI-safe. Here are two common strategies:
Keep Cash Value Under $1,500
For small burial policies, make sure the cash value never goes over $1,500. This may mean choosing a lower coverage amount or checking the growth each year.
Use An Irrevocable Funeral Trust
An irrevocable funeral trust (IFT) is a special account that can pay for your funeral. Once you put money in, you can’t take it out. The SSA does not count IFTs as resources, so you can set aside more than $1,500 for final expenses without risking SSI.
- How it works: You buy a trust from a funeral home or insurance company. The money is locked and only used for burial.
- Limits: Some states limit how much you can set aside.
Assign Policy Ownership
In some cases, you can make another person the owner of your policy. This removes the cash value from your assets. But be careful: You lose control, and this may have tax effects.
Frequently Asked Questions
What Happens If My Life Insurance Cash Value Goes Over The Ssi Limit?
If your cash value grows above $1,500 and you are also close to the $2,000 resource limit, SSI may stop your benefits. You must report this to the Social Security office. You might be able to spend down your resources or cash out the policy, but act quickly.
Can I Use A Term Life Insurance Policy With Ssi?
Yes. Term life insurance does not build cash value, so it will not count against your SSI resources. It is one of the safest types of life insurance for SSI recipients.
What Is An Irrevocable Funeral Trust And How Does It Help?
An irrevocable funeral trust is a fund set aside only for funeral expenses. Once money is placed in this trust, it cannot be used for any other purpose and does not count as a resource for SSI. This is a smart way to set aside more than $1,500 for burial without risking your benefits.
How Do I Report Life Insurance To Social Security?
You should notify your local Social Security office about any life insurance policy you have. Bring your policy documents so they can check the cash value and coverage amount. Not reporting can lead to overpayments and penalties.
Are All Burial Insurance Policies Safe For Ssi Recipients?
Not always. Only the first $1,500 of cash value in a burial policy is exempt for SSI recipients. If the cash value goes over that amount, the extra counts as a resource and could affect your benefits.
Practical Example: Comparing Policies
Let’s look at an example for two common policies:
| Policy Type | Coverage Amount | Premium (per month) | Cash Value at Year 5 | SSI Impact? |
|---|---|---|---|---|
| Term Life | $25,000 | $18 | $0 | No |
| Final Expense | $10,000 | $42 | $890 | No (if under $1,500) |
| Whole Life | $20,000 | $65 | $2,300 | Yes (over limit) |
Insight: Many people do not realize that even small final expense policies can be safe if the cash value is watched closely. But large whole life policies are risky for SSI unless you use a trust.
Non-obvious Insights For Ssi Recipients
- Annual policy reviews are crucial. The cash value in whole life or burial policies grows each year. Many recipients lose benefits simply because they forget to check their policy’s value as it increases.
- State rules can differ. Some states have unique rules for burial funds or trusts. Always check with your state’s Medicaid or Social Security office before making changes.
Where To Get Help
If you’re unsure, speak to a life insurance agent who understands SSI, or contact a non-profit that helps people with disabilities. You can also read official information from the Social Security Administration at SSA.gov.
Finding the best life insurance for SSI recipients is not just about price or brand. The policy you choose must fit strict rules to protect your benefits and your family. By understanding the types of policies, the resource limits, and the safest strategies, you can get the coverage you need with peace of mind.
Take your time, ask questions, and always check the rules before you buy. Your loved ones—and your SSI—are worth it.