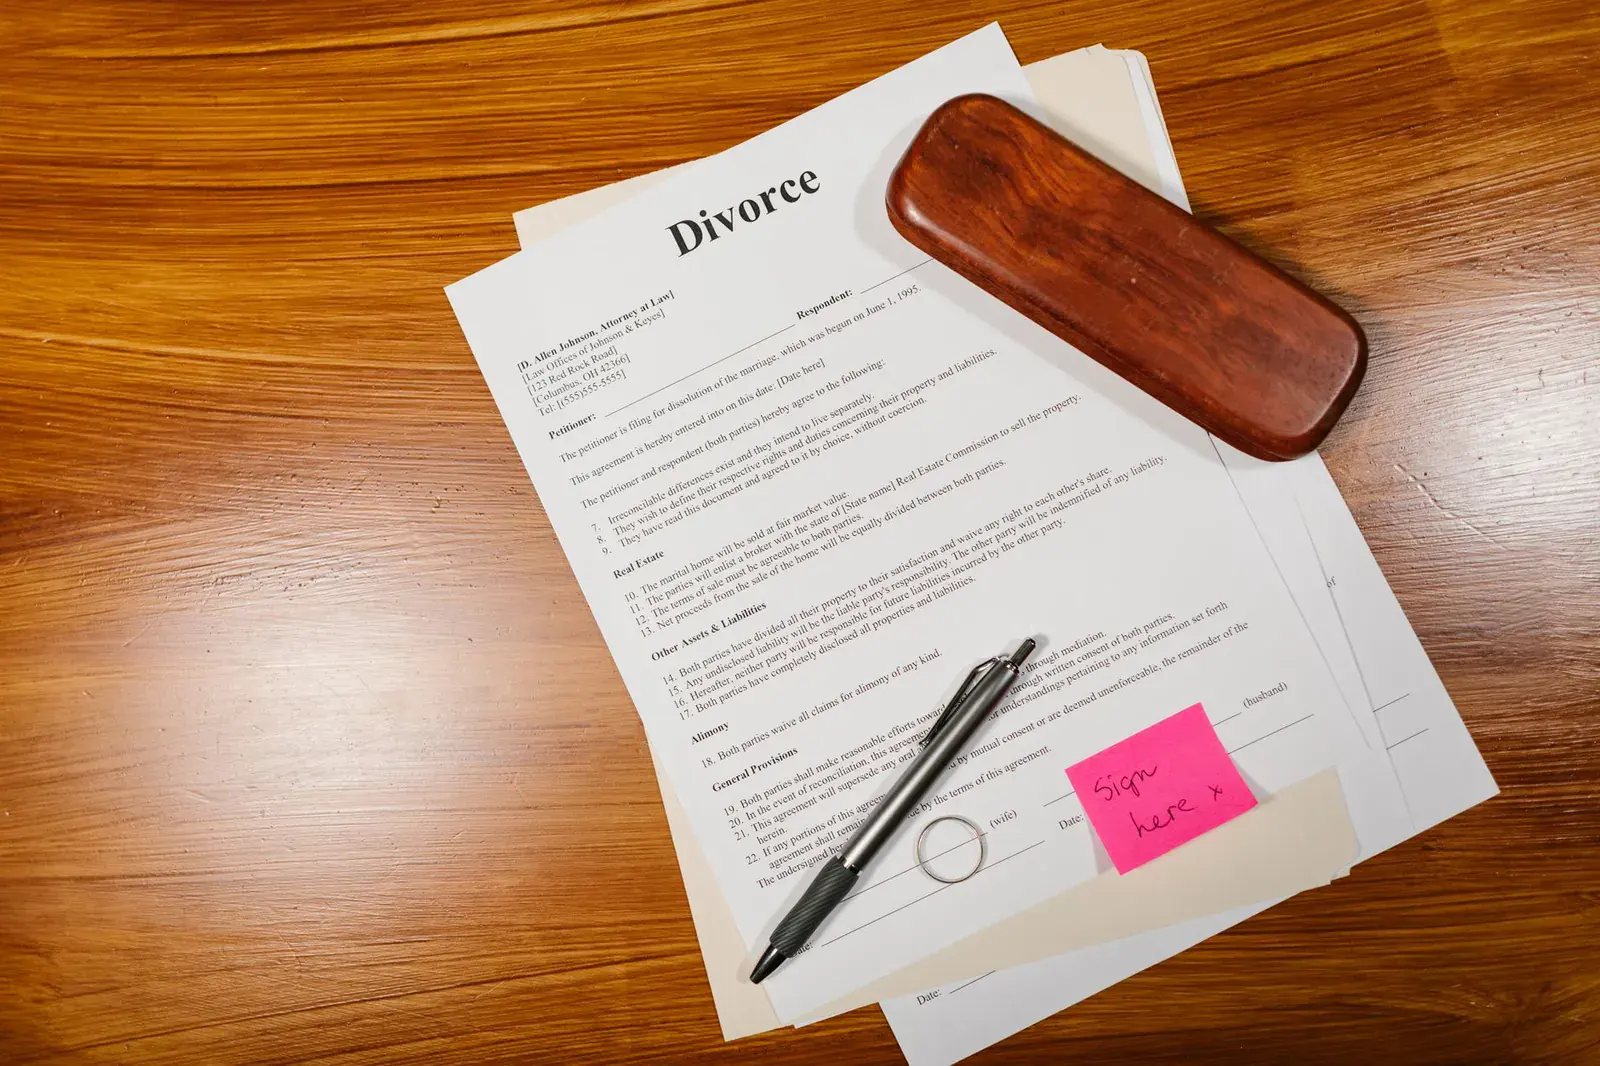
Yes, divorce can affect your life insurance policy, but the policy itself doesn’t change on its own. The insurance company keeps the contract exactly as it is. What changes is who you meant to protect, who can claim the money, and whether the premiums still get paid. In most cases, the real problem isn’t the policy — it’s the beneficiary form nobody updated.
What Happens to the Policy After a Divorce
The policy stays active as long as you keep paying the premiums. Your insurer doesn’t cancel it, raise the price, or send a notice just because a marriage ended. The contract you signed is still the contract.
What can change is the money side. If your ex-spouse was paying the premiums and stops, the policy lapses. If you had a joint plan, you may now need your own separate coverage. And if the court ordered one of you to keep a policy in force for child support or alimony, letting it lapse can put you in legal trouble.
The beneficiary is the part people get wrong. A divorce decree doesn’t automatically remove your ex from your life insurance. In many US states, a divorce revokes a former spouse as beneficiary on older policies unless you file a new form — but rules differ, so check with your state’s insurance department and your insurer directly. The safest move is to submit a new beneficiary form yourself.
Who Gets the Money If You Don’t Update It
Whoever is named on the insurer’s latest beneficiary form gets the payout — not whoever you intended, and not always whoever the divorce papers say. This is where families get hurt.
| Situation | Who usually receives the payout |
|---|---|
| Ex-spouse still listed, form never changed | Often the ex-spouse, depending on state law |
| No beneficiary named at all | Your estate, which may go through probate |
| New spouse or children added by form | The new person you named |
| Minor child named directly | A court-appointed guardian manages the money |
If you name a minor child, the insurer won’t hand a large sum to a child. A court usually appoints someone to hold it, and that takes time and paperwork. Many parents set up a trust instead so the money is managed the way they want.
Tip: After any divorce, request a fresh beneficiary form from your insurer and send it back by a method you can prove, like certified mail or the company’s online portal.
Should You Keep, Change, or Cancel the Policy?
It depends on why you bought it. If the policy exists to protect children, keep it and update the beneficiary. If it only protected your ex, you may not need it anymore.
If you have children or a mortgage that someone else now depends on, keep the coverage and fix the names. If the policy was purely for your ex and no one else relies on it, cancel it and stop the payments.
The trade-off is real. Canceling frees up cash each month, but you give up a policy you may have locked in at a lower rate when you were younger. Replacing it later often costs more because premiums rise with age and health changes.
This isn’t for you if the court ordered the coverage as part of the divorce settlement. In that case, canceling can be treated as breaking a court order, so talk to your attorney first.
One mistake people make is assuming the divorce “takes care of it.” They stop thinking about the policy, keep paying for years, and the money still goes to an ex-spouse. The cost is the entire death benefit going to the wrong person.
Frequently Asked Questions
Can my ex-spouse still claim my life insurance after divorce?
Sometimes yes. If your ex is still listed as beneficiary on the insurer’s records, they may receive the payout, depending on your state’s law. Submitting a new beneficiary form in writing is the only reliable way to remove them.
Does divorce change my premium or coverage amount?
No. The insurer prices your policy on your age, health, and the coverage amount, not your marital status. Your premium and death benefit stay the same unless you ask to change them.
What if the divorce decree says my ex must keep the policy?
Then it’s a legal obligation, not just a personal choice. Canceling or letting it lapse could be a violation of the court order. Keep paying and speak with your attorney before making any change.
Conclusion
Pull out your policy and check the beneficiary line this week. If it still names your ex, contact your insurer and file a new form, then keep a copy for your records. One short form protects the people you actually meant to provide for.