
Life insurance can be a confusing topic, especially if you are searching for the lowest price. Most people want to protect their family, but they also don’t want to overspend. The truth is, there are many ways to get cheapest life insurance without sacrificing too much. You just need to know where to look, what to ask, and how to avoid the common traps that make insurance expensive. This article will guide you step by step—using simple words, clear explanations, and real examples. If you want to save money and make a smart choice, keep reading.
Why Life Insurance Prices Vary So Much
Many people wonder why two people pay very different prices for similar life insurance. The answer is in how companies calculate risk. They look at your age, health, lifestyle, and even your job. For example, a healthy 25-year-old usually pays much less than a 55-year-old smoker. Insurance companies use statistics and data to decide your monthly cost.

Let’s see how prices can differ:
| Profile | Monthly Cost (20-year term, $250k coverage) |
|---|---|
| Healthy 30-year-old | $14 |
| Healthy 50-year-old | $56 |
| Smoker, 40 years old | $76 |
| Diabetic, 35 years old | $43 |
As you can see, age and health make a big difference. But there are ways to keep your costs low, even if you are not young or perfectly healthy.
Key Steps To Get The Cheapest Life Insurance
Getting the lowest price is not just about choosing the cheapest company. You need to follow a few important steps. Let’s break them down one by one.
1. Decide What Coverage You Really Need
Many people buy too much insurance. You do not need a million-dollar policy if your family would be fine with $250,000. To find the right amount:
- Think about your debts (mortgage, car loans)
- Add your children’s education costs
- Consider daily living expenses for your family
A good rule: Buy enough to cover these needs, but not more. If you buy extra, your price goes up fast.
2. Choose Term Life Insurance
There are two main types: term life and whole life. Term life is much cheaper because it covers you for a set period (10, 20, or 30 years). Whole life covers you for your entire life and has cash value, but costs much more.
Here’s a quick comparison:
| Type | Monthly Cost (30-year-old, $250k coverage) | Coverage Length | Cash Value? |
|---|---|---|---|
| Term Life | $14 | 20 years | No |
| Whole Life | $130 | Lifetime | Yes |
For most people, term life is the best way to get cheap life insurance.
3. Compare Quotes From Multiple Companies
Never buy from the first company you find. Prices can change a lot between companies. Use online quote tools, or ask an insurance broker. Look for at least three quotes.
Here are a few tips:
- Get quotes from big brands and smaller companies
- Make sure you use the same coverage amount and term when comparing
- Ask if there are any discounts for healthy living or bundling other insurance
4. Improve Your Health Before Applying
Insurance companies check your health with a medical exam. If you can improve your health before applying, your price will drop. Some ways to do this:
- Quit smoking at least 12 months before applying
- Lose weight if you are overweight
- Control blood pressure and cholesterol
Even small improvements can make a big difference. For example, quitting smoking can cut your monthly price by more than half.
5. Avoid Extra Riders Unless Needed
Insurance companies offer riders—extra coverage options for things like accidents or disability. Each rider adds to your cost. Only choose riders you really need. For most people, basic life insurance is enough.
6. Buy When You Are Young
The younger you are, the cheaper your life insurance. If you wait until you are older, your price goes up every year. Even a delay of five years can double your monthly cost.
7. Pick The Shortest Term That Fits Your Needs
A 30-year policy costs more than a 10-year policy. Think about how long your family needs support. If your kids are young, maybe 20 years is enough. If you are close to retirement, a shorter term may work.
8. Check Group Life Insurance From Work
Some employers offer group life insurance. This is often very cheap, or even free. But the coverage may be limited. Still, it can be a good option for basic protection.
9. Consider No-exam Policies Carefully
Some companies offer no-exam life insurance. You don’t have to take a medical test, but the price is usually higher. Only use this if you have health issues and cannot pass a medical exam.
10. Bundle Insurance Policies
Some companies offer discounts if you buy home, auto, and life insurance together. Ask about bundling discounts when getting quotes.
Secrets Most People Miss When Looking For Cheap Life Insurance
Many people focus only on the monthly price. But there are hidden tricks that can make your life insurance even cheaper.
Pay Annually, Not Monthly
Insurance companies often charge extra if you pay monthly. If you can pay once a year, you may save up to 10%.
Use Laddering
Laddering means buying several term policies with different end dates. For example:
- $150,000 for 10 years
- $100,000 for 20 years
This fits your needs as your debts or kids grow up, and you pay less overall. Most beginners do not know about this tactic, but it works well.
Shop During “open Enrollment” Periods
Some workplaces or groups offer special rates during open enrollment. You can get cheaper prices if you apply during this time.
Ask For A Healthy Lifestyle Discount
Some companies give discounts for gym memberships, running marathons, or keeping low cholesterol. Always ask if you qualify for these.
Common Mistakes That Make Life Insurance Expensive
Avoiding mistakes is just as important as finding deals. Here are some errors that can raise your costs:
- Waiting too long to buy—prices go up every year.
- Buying whole life when term life fits your needs.
- Adding too many riders—extra options cost more.
- Not shopping around—prices differ a lot.
- Underestimating health impact—even small health problems can double your price.
Example Of How Mistakes Can Cost You
Imagine two people:
- Anna, age 35, buys term life, shops around, and gets $250k coverage for $18 a month.
- Ben, age 38, waits three years, adds riders, and buys whole life. He pays $150 a month for similar coverage.
Over 20 years, Anna pays $4,320. Ben pays $36,000. That’s a huge difference—just because Ben made common mistakes.

How To Apply For Cheap Life Insurance Step By Step
The application process can seem hard, but it’s actually simple if you know what to do.
- Research companies online or talk to a broker.
- Compare quotes for the same coverage and term.
- Fill out the application—be honest about health and habits.
- Take the medical exam (if needed)—prepare by eating healthy and staying active.
- Review the final offer—check for errors or hidden fees.
- Choose payment plan—annual or monthly.
- Sign the policy—make sure you get all documents.
Most applications take about 2–4 weeks from start to finish. No-exam policies are faster, but cost more.
How Insurers Decide Your Price
Understanding how insurers set your price helps you get the lowest rate. Here are the main factors:
| Factor | Impact on Price | How to Improve |
|---|---|---|
| Age | Older = higher price | Buy young |
| Health | Poor health = higher price | Improve fitness, quit smoking |
| Coverage Amount | More coverage = higher price | Buy only what you need |
| Policy Type | Whole life = much higher price | Choose term life |
| Riders | Extra options = higher price | Skip unnecessary riders |
| Payment Plan | Monthly = slightly higher price | Pay annually |
If you understand these factors, you can adjust your choices to get the cheapest price.
Real-world Data: Cheapest Life Insurance By State
Prices also change based on where you live. Some states have higher costs due to health trends and laws. Here’s a sample for a healthy 30-year-old, $250k coverage, 20-year term:
| State | Average Monthly Cost |
|---|---|
| California | $16 |
| Texas | $14 |
| New York | $18 |
| Florida | $15 |
| Illinois | $13 |
If you move or plan to live in another state, check local prices before buying.
How To Use Online Tools To Find Cheap Life Insurance
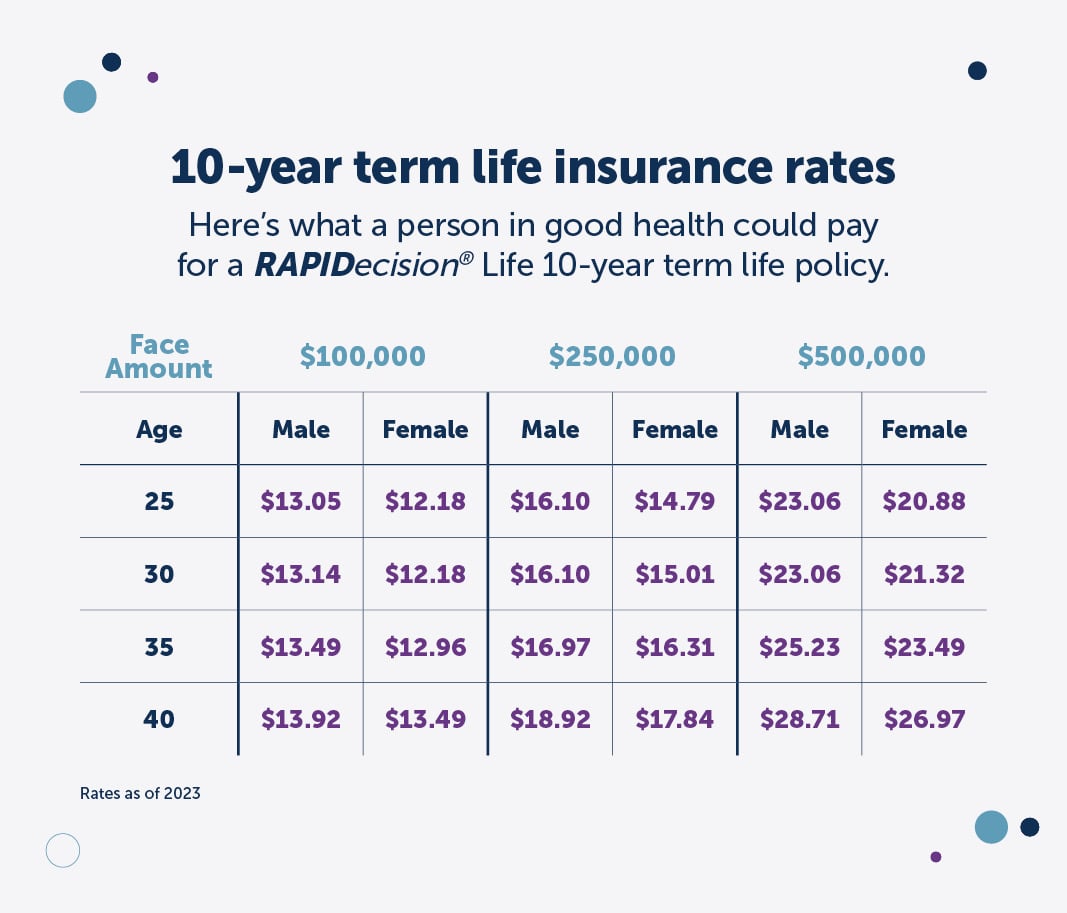
Online quote tools make comparing prices fast and easy. Here’s how to use them:
- Fill in your age, health details, and coverage amount
- Compare multiple companies side by side
- Look for special offers or discounts
- Read reviews to check company reliability
One useful site is NerdWallet, which explains how to compare life insurance quotes online.
Hidden Costs And Fees To Watch Out For
Some insurance policies come with hidden costs. Always check:
- Administrative fees—some companies charge extra for paperwork
- Policy fees—small monthly charges added to your premium
- Surrender charges—fees if you cancel early (mostly for whole life)
Ask your insurer to explain all fees before you sign.
Tips For Non-native English Speakers
If English is not your first language, buying life insurance can be harder. Here are some tips:
- Ask for documents in your language if possible
- Bring a friend who speaks English well when meeting agents
- Use simple online quote tools
- Avoid complicated policies like whole life or universal life
Some insurers have staff who speak multiple languages. Always ask for help if you need it.
When Cheap Life Insurance Is Not The Best Choice
Cheap is good, but not always best. If you have special needs—like a disabled child, or a risky job—you may need a bigger policy or extra riders. Think carefully about your family’s future. Saving money is important, but protecting your loved ones matters more.
Frequently Asked Questions
What Is The Cheapest Type Of Life Insurance?
The cheapest is term life insurance. It covers you for a set period (10, 20, or 30 years) and costs much less than whole life or universal life.
Does My Health Affect Life Insurance Price?
Yes. If you are healthy, you pay much less. Health issues like smoking, diabetes, or high blood pressure raise your price. Improving your health before applying can save you money.
Can I Get Cheap Life Insurance Without A Medical Exam?
Yes, but it usually costs more. No-exam policies are easy and fast, but the price is higher. If you are healthy, taking the medical exam is better.
How Much Life Insurance Do I Really Need?
Add up your debts, living costs, and any future needs (like college for your kids). Only buy what you need. Most people do not need more than $250,000–$500,000 in coverage.
Is Group Life Insurance From Work Enough?
Group insurance from your job is a good start and often cheap. But coverage is limited. You may need extra insurance to fully protect your family.
Getting the cheapest life insurance is not hard if you know what to do. Decide what you need, choose term life, compare prices, and avoid common mistakes. Always think about your family’s needs first. If you follow these steps, you can save thousands of dollars and still protect your loved ones. Remember—buying life insurance is one of the most important financial decisions you will make. Take your time, ask questions, and make the best choice for your situation.