Looking for the cheapest place to get term life insurance? You’re not alone. Many people want to protect their family without paying high prices. But where do you really find the best deals? And how can you be sure you’re not missing something important? If you’re new to insurance, the choices and details can feel confusing. Let’s break it down simply, so you can find the right coverage for your needs and budget.
What Is Term Life Insurance?
Term life insurance is a simple way to protect your family if something happens to you. You pay a fixed amount every month or year. If you die during the policy term (for example, 10, 20, or 30 years), your family receives a fixed amount of money (the “death benefit”). If you’re still alive when the term ends, the policy usually stops and you get nothing back.

This makes term life insurance much cheaper than “whole life” insurance, which covers you for your entire life and has savings features.
Why People Choose Term Life
- Low cost compared to other types of life insurance
- Easy to understand
- Flexible lengths (you can choose how many years you want coverage)
What Affects The Price Of Term Life Insurance?
Before you look for the cheapest place, it helps to know what affects the price. Insurance companies use many factors to decide how much you pay. Some you can control, and some you can’t.
Main Factors
- Age: The younger you are, the cheaper your insurance.
- Health: Good health means lower prices. Smokers or people with health problems pay more.
- Coverage amount: The more money you want your family to get, the higher the cost.
- Term length: Longer terms cost more.
- Gender: Women often pay less because they usually live longer.
- Lifestyle: Risky jobs or hobbies (like skydiving) increase the price.
Example: How Much Can Prices Change?
Here’s a look at how different factors affect monthly costs for a 20-year, $500,000 policy.
| Person | Age | Smoker? | Monthly Cost |
|---|---|---|---|
| Healthy Woman | 30 | No | $18 |
| Healthy Man | 30 | No | $21 |
| Healthy Man | 40 | No | $32 |
| Man | 40 | Yes | $87 |
As you can see, being younger and not smoking makes a big difference.
Where Can You Get The Cheapest Term Life Insurance?
Finding the cheapest place is not just about picking the first company you see online. Prices change based on your personal situation and where you shop. Here are the main places to look:
1. Online Insurance Marketplaces
Websites like Policygenius, Quotacy, and SelectQuote let you compare prices from many companies at once. You fill in your details, and they show you options from big insurers. This helps you see a range of prices quickly.
Pros:
- Easy to compare many companies
- Often find the lowest rates
Cons:
- Some sites ask for contact info and may call you later
2. Direct-to-consumer Insurance Companies
Some companies sell insurance directly online, without agents. Examples are Bestow, Ladder, and Haven Life. You can apply, get approved, and pay online—sometimes without a medical exam if you’re healthy.
Pros:
- Fast and simple
- May skip the medical exam
Cons:
- Not all people qualify for no-exam policies
- Fewer choices than marketplaces
3. Traditional Insurance Companies
Big names like State Farm, Prudential, and Northwestern Mutual offer term life insurance. You usually talk to an agent. Sometimes they have good deals, but often their prices are a bit higher because of agent fees.
Pros:
- Personal help from an agent
- Trusted brands
Cons:
- May cost more
- Takes longer to compare prices
4. Credit Unions And Group Plans
Some employers, credit unions, or groups offer life insurance as a benefit. Prices can be low, but coverage amounts are often small, and you may lose coverage if you leave the job or group.
Pros:
- Low cost
- Easy to join
Cons:
- Coverage can end if you leave the group
- Not always enough coverage for most families
Cheapest Term Life Insurance Companies (2024)
Every year, some companies offer lower prices than others. In 2024, these insurers are known for cheap term life insurance, especially for healthy people:
| Company | Monthly Cost (Male, age 30, $500k, 20 yrs) | Medical Exam Needed? |
|---|---|---|
| Haven Life | $20 | Sometimes |
| Banner Life | $19 | Usually |
| Protective | $18 | Usually |
| Bestow | $21 | No |
| Lincoln Financial | $20 | Usually |
Prices can change based on your health, age, and other factors. Always compare a few companies before choosing.
How To Get The Cheapest Rate: Step-by-step
Getting cheap term life insurance is not just about picking a company. You can take steps to lower your cost before you buy.
Steps To Save Money
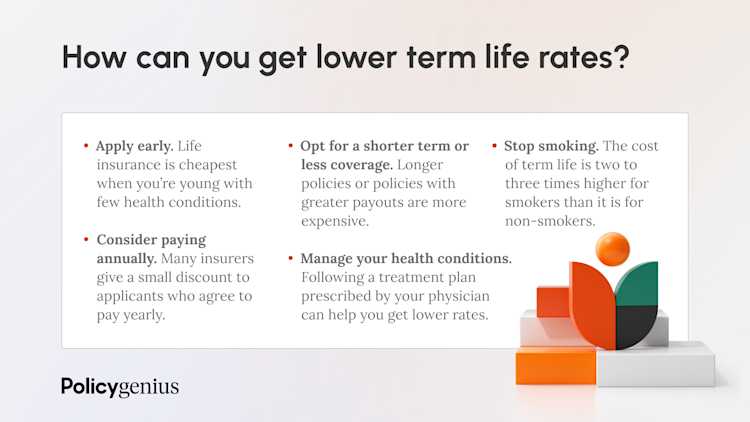
- Shop early: Prices go up as you age. Buying younger saves money every year.
- Compare quotes: Always check at least three companies. Prices can be very different for the same person.
- Improve your health: Lose weight, stop smoking, and control blood pressure or cholesterol if you can. Even small changes can help.
- Choose the right coverage: Don’t buy more than you need. Many people pick a policy much bigger than their family will use.
- Pick the shortest term you need: If your kids will be grown in 15 years, you may not need a 30-year policy.
- Ask about discounts: Some companies give lower rates if you pay yearly or have other policies (like auto insurance) with them.
- Be honest on your application: Lying about your health or habits can cancel your policy later.
Example: The Power Of Comparison
Let’s say you’re a healthy, non-smoking woman, age 35, looking for $250,000 coverage for 20 years. If you only check one company, you might pay $16/month. But if you compare three, you might find another for $11/month. Over 20 years, that’s a savings of $1,200.
Common Mistakes When Shopping For Cheap Term Life Insurance
Many beginners make the same errors when looking for the cheapest policy. Here’s what to avoid:
- Only looking at price: The cheapest policy is not always the best. Make sure the company is strong and will pay claims if needed.
- Not reviewing policy details: Some cheap policies have tricky rules or limits. Read the fine print or ask questions.
- Skipping the medical exam: No-exam policies are easier but can cost more. If you’re healthy, taking the exam can save you money.
- Forgetting to update your policy: Life changes—like a new child or a new house—may mean you need more coverage later.

Non-obvious Tips For Extra Savings
Most guides stop at the basics, but here are two things beginners often miss:
1. Laddering Policies: Instead of buying one big policy for 30 years, you can buy two or three smaller policies with different lengths. As your kids grow or debts shrink, your coverage drops and so do your costs.
2. Ask about Conversion Options: Some term policies let you switch to “whole life” later with no health questions. Even if you want cheap term now, having this option can be valuable if your health changes.
How To Check Company Strength
A cheap policy is only good if the company will be there when your family needs it. Look for companies with strong financial ratings (A or higher from AM Best, Moody’s, or Standard & Poor’s). You can check ratings for free online.
When Cheap Isn’t Best: Watch For Red Flags
- Very low prices compared to others can mean limited coverage or companies with bad service.
- Pushy sales tactics often hide extra fees or weak policies.
- No clear policy documents: Always get written details before you pay.
Real-world Example
Maria is a 28-year-old non-smoker. She uses an online marketplace, gets quotes from five companies, and chooses a 20-year, $500,000 policy for $17/month from Banner Life. She takes the medical exam, saves $4/month compared to a no-exam option, and puts the savings toward her emergency fund.
By comparing and not just picking the first offer, Maria saves $960 over 20 years.
Quick Comparison: Online Marketplaces Vs. Direct Companies
Here’s a simple side-by-side look at your main choices.
| Option | Pros | Cons |
|---|---|---|
| Online Marketplace | Many quotes, easy compare | May get sales calls |
| Direct Online Company | Fast, simple, sometimes no exam | Fewer choices |
| Traditional Agent | Personal help, trusted brands | Usually higher cost |
Useful External Resource
For more details about how life insurance works, you can check this guide from NerdWallet.
Final Thoughts
Finding the cheapest place to get term life insurance means looking beyond just the lowest price. Compare quotes from online marketplaces and direct companies, and check that the insurer is strong and easy to work with. If you’re healthy, a medical exam can save you money. Remember, coverage is about protecting your family—not just getting the lowest cost. Take your time, ask questions, and don’t rush. The right term life insurance gives you peace of mind without breaking your budget.
Frequently Asked Questions
What Is The Best Age To Buy Term Life Insurance?
It’s best to buy term life insurance when you’re young and healthy, usually in your 20s or 30s. Prices are lower, and you can lock in cheap rates for many years.
Do I Need A Medical Exam To Get Cheap Term Life Insurance?
Not always. Some companies offer no-exam policies, but these can cost more. If you’re healthy, taking the exam usually means lower prices.
How Much Term Life Insurance Should I Buy?
Most people need 10–12 times their yearly income. Consider your debts, living expenses, and family needs. Don’t buy more than you need.
Can I Switch Companies If I Find A Cheaper Rate Later?
Yes, you can switch. But get your new policy before canceling the old one. Make sure your health hasn’t changed, or the new policy might cost more.
What Happens If I Outlive My Term Life Insurance?
If you’re still alive when the policy ends, the coverage stops, and you get nothing back. Some policies let you renew or convert to another type, but it will likely cost more.