
Life insurance is one of those things many people know they need, but few are sure how much to buy. If you buy too little, your loved ones might struggle financially. If you buy too much, you could be wasting money on higher premiums.
Finding the right balance is important for protecting your family and your wallet.

Why Life Insurance Coverage Matters
Life insurance is there to help your family pay for important things if you pass away. This could include:
- Daily living expenses
- Mortgage or rent payments
- College fees for your children
- Outstanding debts
- Funeral costs
The right amount of coverage will help your family maintain their lifestyle and avoid financial stress. Underestimating your needs is a common mistake. Many people only think about funeral costs, but forget about ongoing expenses.
How To Calculate Your Life Insurance Needs
There isn’t a one-size-fits-all answer, but there are simple methods to estimate your coverage needs.
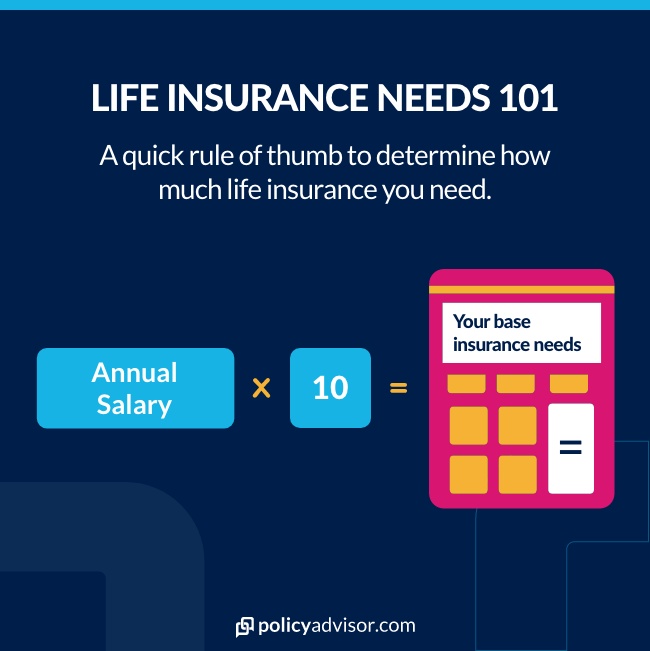
1. The 10x Income Rule
A common rule of thumb is to buy life insurance equal to 10 times your annual income. For example, if you earn $50,000 a year, you might start with $500,000 in coverage.
But this rule doesn’t consider your unique situation. It ignores your debts, children’s education costs, or other financial goals.
2. The Dime Method
This method helps you break down your needs into four parts:
- Debt: Add up all your debts except your mortgage.
- Income: Multiply your yearly income by the number of years your family will need support.
- Mortgage: Add the amount left on your mortgage.
- Education: Estimate the cost of sending your children to college.
Let’s see a quick example:
| Category | Amount |
|---|---|
| Debt | $20,000 |
| Income (10 years) | $500,000 |
| Mortgage | $150,000 |
| Education | $80,000 |
| Total Needed | $750,000 |
3. Custom Calculation
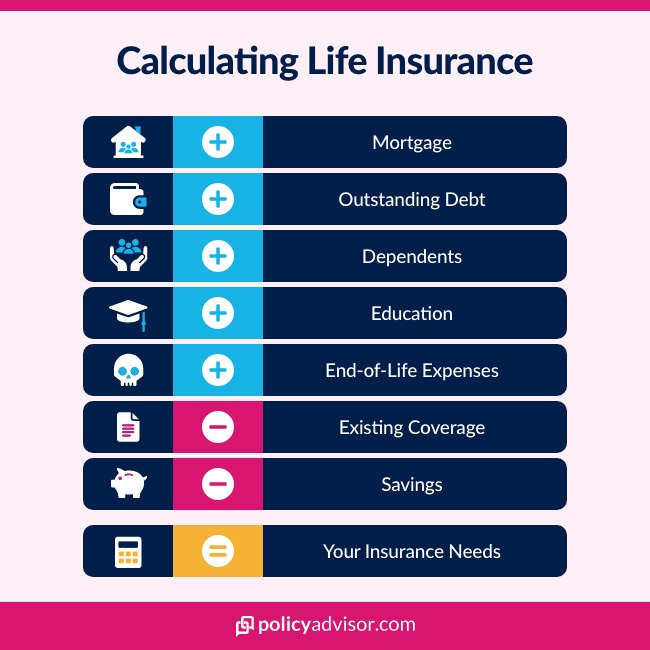
For more accuracy, consider your family’s future needs and current assets. Subtract what you already have (like savings or investments) from what your family will need.
Formula:
(future Expenses And Debts) – (current Assets) = Coverage Needed
Example: If your family will need $800,000 but you have $100,000 in savings, you need $700,000 in coverage.
Credit: www.policyadvisor.com
Factors That Affect How Much Life Insurance You Need
Every family is different. Here are important things to consider:
Your Family’s Lifestyle
Think about your family’s standard of living. Will your spouse work or stay home? Do you want your children to attend private school or college? Higher goals mean higher coverage.
Debts And Loans
Mortgage, car loans, and personal debts should all be covered. Don’t forget about student loans if you co-signed for them.
Dependents
If you have young children or dependents with special needs, you’ll need more coverage. Older children may require less, especially if they’re financially independent.
Final Expenses
Funerals can be expensive. The average funeral in the US costs $7,000 to $12,000. Make sure your policy covers this.
Existing Coverage And Assets
If you already have some life insurance through work or other sources, subtract this from your total need.
How Much Do Most People Buy?
Studies show the average life insurance policy in the US is around $168,000. However, this is often not enough for families with children, mortgages, and other big expenses.
Here’s a quick comparison of coverage amounts and who they might suit:
| Coverage Amount | Who It’s For |
|---|---|
| $100,000 | Single adults, no dependents |
| $250,000 | Young families, small debts |
| $500,000 | Average family, mortgage |
| $1,000,000+ | High earners, multiple dependents |
Common Mistakes To Avoid
- Relying only on employer coverage: Most job-based insurance is not enough and may not follow you if you leave the company.
- Ignoring inflation: Costs rise over time. A $500,000 policy today won’t have the same value in 20 years.
- Not updating your policy: Review your coverage after big life changes, such as marriage, having a baby, or buying a house.
- Forgetting about stay-at-home parents: If a stay-at-home parent dies, the cost of childcare and home duties can be high.
How Premiums Change With Coverage
The more coverage you buy, the higher your premium. But sometimes, doubling your coverage does not mean your cost will double. Here’s a simple comparison for a healthy 35-year-old buying term life insurance:
| Coverage Amount | Monthly Premium |
|---|---|
| $250,000 | $20 |
| $500,000 | $35 |
| $1,000,000 | $60 |
You might notice that higher coverage can give you more value per dollar.

Credit: www.physiciansidegigs.com
Adjusting Your Coverage Over Time
Your need for life insurance changes as your life does. When your children grow up, or you pay off your mortgage, you may not need as much coverage. Some people buy a large policy when their kids are young, then reduce coverage later.
Getting Advice
Choosing the right amount of life insurance can be confusing. A trusted insurance agent or financial advisor can help you assess your needs. For more information on life insurance basics, you can visit the Insurance Information Institute.
Credit: www.policyadvisor.com
Frequently Asked Questions
How Do I Know If I Have Enough Life Insurance?
Check if your coverage will replace your income, pay off debts, and cover future expenses for your family. If your policy falls short in any area, you may need to increase it.
Is Employer-provided Life Insurance Enough?
Usually, employer plans offer only 1-2 times your salary, which is rarely enough for families. It’s smart to buy extra coverage on your own.
Should Stay-at-home Parents Have Life Insurance?
Yes. They provide valuable services like childcare, which would be expensive to replace. Life insurance can help cover these costs.
How Often Should I Review My Life Insurance Needs?
Review your coverage every few years, or after major life changes like marriage, children, or buying a home.
What Happens If I Buy Too Much Life Insurance?
You’ll pay higher premiums than needed. It’s better to buy the right amount based on your real needs and review it as your life changes.
Getting the right life insurance coverage is not about guessing. Take a careful look at your family’s needs, your debts, and your goals. The right policy will give you peace of mind, knowing your loved ones are protected—no matter what happens.